The Right Order to Make Home Decisions

Homeownership comes with choices. Renovate the kitchen. Turn the property into a rental. Refinance the mortgage. Sell and move on.

Each option can make sense on its own. But what many homeowners miss is that these choices rarely exist in isolation. The order you make them in matters.

That is why understanding the right order to make home decisions can save time, money, and frustration.

When decisions happen out of sequence, one move can quietly block another.

Many homeowners start with renovations. They assume improvements will increase value and make the home easier to sell or rent later. Sometimes that works. But often those upgrades cost more than they return, especially if they are done without a clear long-term plan.

Before making improvements, it helps to step back and ask a simple question. What is the final goal?

If you plan to sell within the next year or two, large renovations may not be necessary. Buyers often value clean, well-maintained homes more than expensive remodels that push the price beyond the neighborhood range.

Understanding the right order to make home decisions means identifying the destination before spending money on the journey.

Renting is another option that can change the path forward. Many homeowners consider turning their property into a rental instead of selling. The idea of generating income while holding onto the asset can sound appealing.

But becoming a landlord introduces new variables. Maintenance, tenant turnover, property management, and local regulations all affect profitability. Rental income also changes how lenders evaluate your finances if you plan to purchase another property later.

In some cases, renting first makes sense. In other cases, it complicates future plans.
Happy family with agent realtor near new house.

That is why the right order to make home decisions requires thinking about both lifestyle and long-term flexibility.

Refinancing is another step that often happens too early. Lower payments or tapping into equity can sound attractive, especially when interest rates shift. But refinancing resets loan terms and adds closing costs. It may also reduce your ability to move quickly if circumstances change.

If selling is even a possibility within the next few years, refinancing should be evaluated carefully. The savings may not outweigh the cost if you do not stay in the home long enough.

When homeowners understand the right order to make home decisions, refinancing becomes a strategic move rather than a reactive one.

Selling is usually the decision that brings everything together. Yet many homeowners delay this step because they believe they must renovate or refinance first. In reality, the market often rewards well-priced homes in good condition without requiring major upgrades.

A clean, functional property with strong presentation can attract buyers quickly. Waiting to complete unnecessary projects may simply delay the process and increase carrying costs.

Sometimes the simplest option is the most efficient.

What matters most is clarity. Are you trying to maximize profit? Reduce monthly expenses? Create rental income? Move closer to work or family? Different goals require different strategies.

Once the goal is clear, the sequence becomes easier to see.
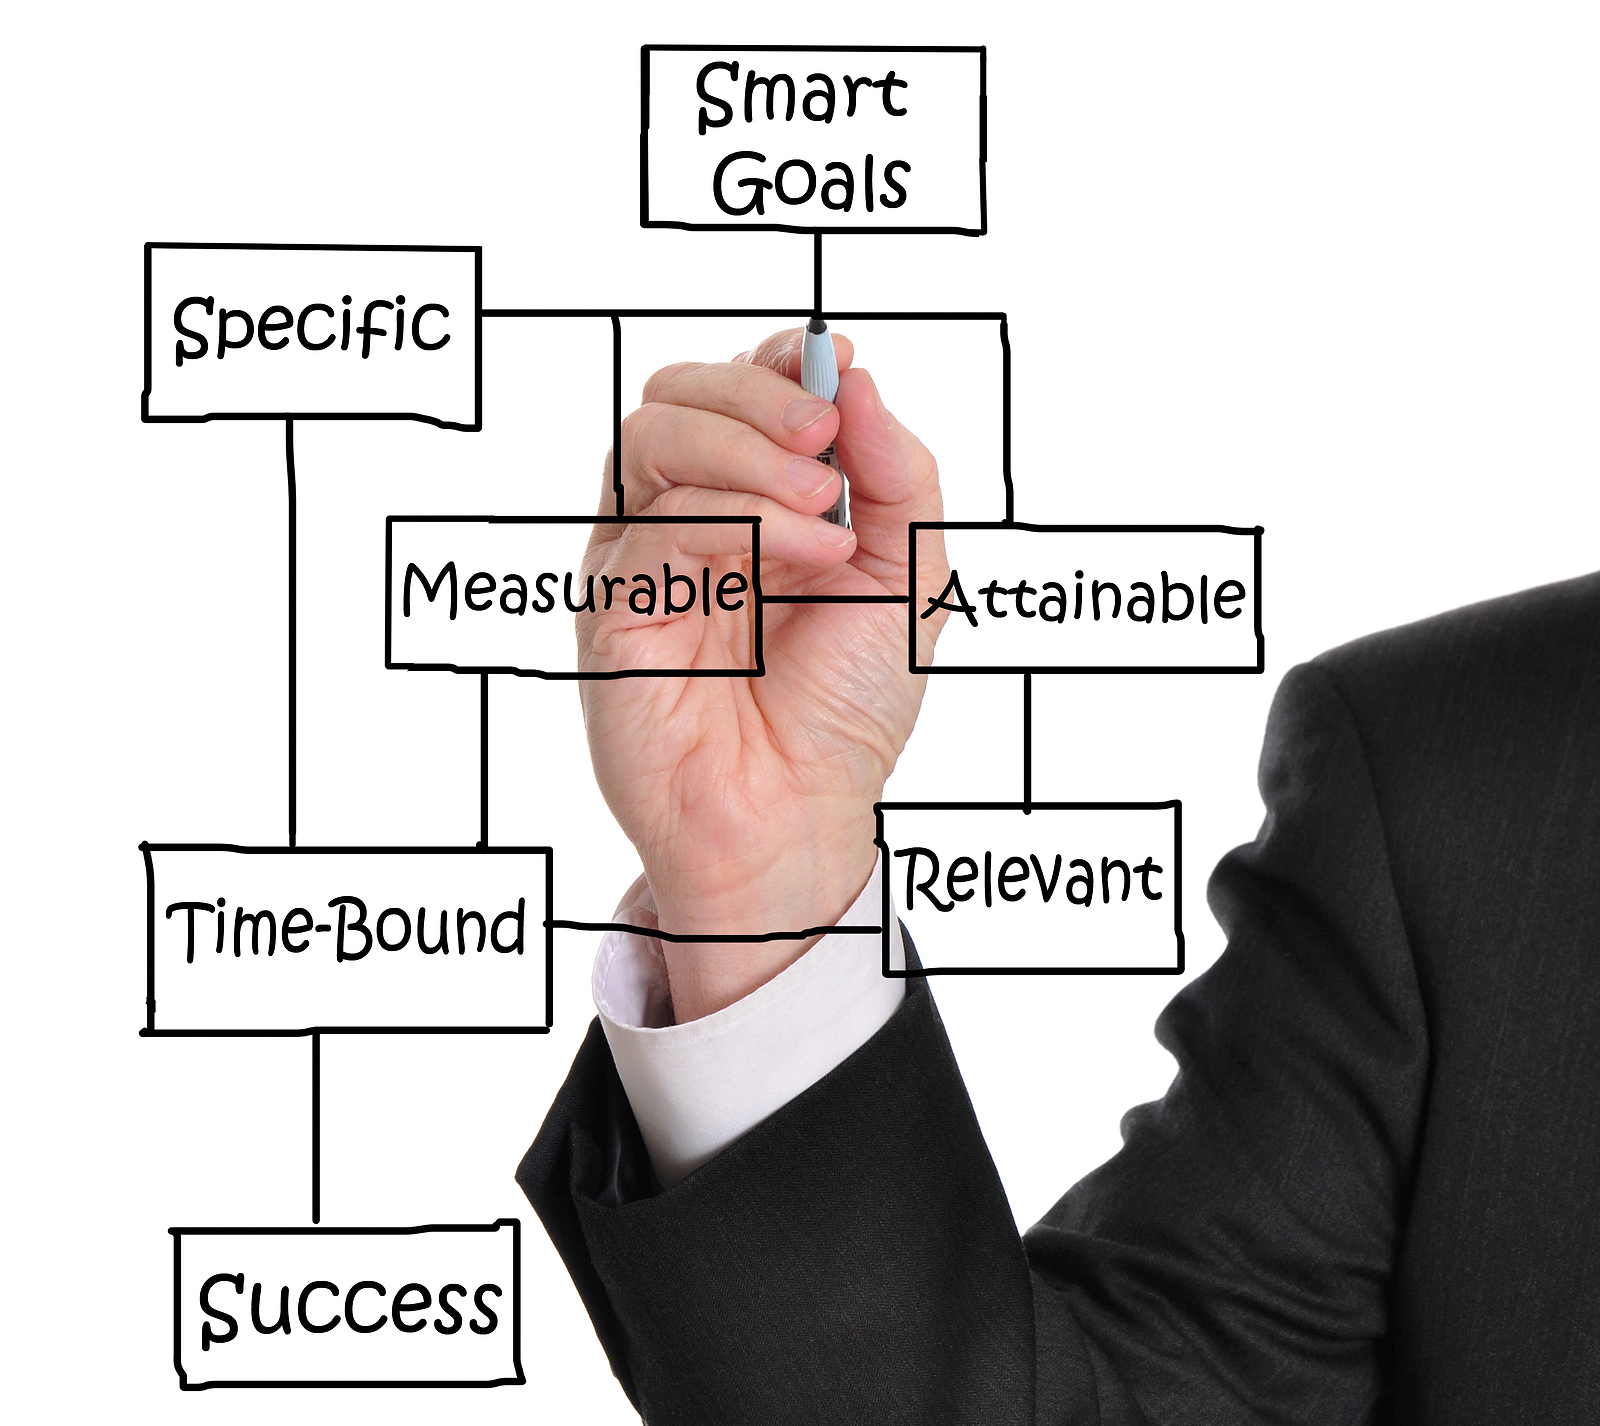
Male executive drawing Smart Goal concept on a whiteboard. Smart Goals lead to success

That clarity is the foundation of the right order to make home decisions. Without it, homeowners risk making choices that limit flexibility or reduce financial return.

For example, renovating heavily before deciding whether to sell may reduce profit. Refinancing before planning a move may create unnecessary costs. Renting without understanding long-term responsibilities may complicate future purchases.

Each decision carries ripple effects.

Thinking through the order of actions helps avoid those unintended consequences. It turns reactive decisions into intentional ones.

Homeownership provides options. But options only create opportunity when they are used in the right sequence.

When homeowners pause to evaluate their goals, timelines, and financial priorities, the path forward becomes clearer.

That is the real value of understanding the right order to make home decisions. It allows each step to support the next instead of working against it.

And when decisions align with both life plans and financial strategy, the process becomes far smoother.

Make Smart Home Decisions. Before you renovate, rent, refinance or sell. Read this!

Young couple buying a home.

Owning a home comes with choices. Renovate. Rent it out. Refinance. Sell and move on.

Each option sounds reasonable on its own. But the mistake many homeowners make is treating these choices separately instead of as connected home decisions.

One move often affects the next.

And the wrong order can quietly cost you thousands.

This is why stepping back and looking at the bigger picture matters before doing anything permanent. The most expensive mistakes usually happen when people act quickly without understanding how one decision limits another.

Smart home decisions start with strategy, not urgency.

One of the biggest myths homeowners believe is that every improvement automatically adds value. It sounds logical. Spend money, increase value, sell for more. But real estate doesn’t always work that way.

Not all upgrades pay you back.

Highly customized renovations, trendy finishes, or expensive projects that don’t match what most buyers want often return far less than expected. In some cases, they make a home harder to sell.

Buyers don’t pay extra for everything you spend. They pay for what they need and what feels move-in ready.

Simple improvements like paint, lighting, and repairs often deliver better results than large remodels. Before investing heavily, ask whether the update helps resale value or simply personal taste.

Good home decisions focus on return, not just improvement.

Renting is another option that looks great on paper. Many homeowners calculate potential rent and assume it will cover the mortgage while building passive income. But the reality is often more complicated.

Rental math can be misleading.

Maintenance costs add up. Vacancies happen. Property management fees cut into profits. Repairs rarely occur at convenient times. What seems like steady income can quickly turn into unpredictable expenses.

There’s also the lifestyle side. Being a landlord means time, responsibility, and risk. For some people, it works well. For others, it becomes more stressful than expected.

Before choosing this path, run the real numbers, not just the optimistic ones. Strong home decisions come from realistic planning.

Refinancing is another move that deserves careful thought. Lower payments can sound appealing, especially when rates change. But refinancing can also limit flexibility.

New loan terms often restart the clock. Fees and closing costs reduce savings. And if you refinance right before selling, you may not stay long enough to break even.

It can also impact your ability to qualify for another purchase if your financial situation changes.

What looks like a short-term win may restrict long-term options. Smart home decisions consider timing just as much as savings.

Then there’s selling. Some homeowners delay selling because they believe they must renovate first or refinance to “get ready.” In many cases, those extra steps aren’t necessary and simply delay the process.

A clean, well-maintained home often sells just as well as one with expensive updates. And waiting too long can mean missing better market conditions.

Sometimes the simplest path is the most profitable.

The biggest issue is how these choices interact. Renovating heavily may reduce profit if you plan to sell soon. Refinancing could make it harder to move quickly. Renting might prevent you from accessing equity when you need it. Each step can block the next.

That’s why big home decisions should never be made in isolation.

They should be made in the right order.

Start with the end goal. Do you want to move soon? Build long-term income? Lower monthly expenses? Once the goal is clear, the right path becomes easier to see.

Without that clarity, it’s easy to spend money or lock yourself into something that doesn’t support where you actually want to go.

Homeownership creates opportunity, but only when choices are intentional.

Before renovating, renting, refinancing, or selling, take the time to look at the full picture. Map out the sequence. Understand the trade-offs. Make decisions that work together, not against each other.

Because the smartest home decisions aren’t about doing more.

They’re about doing the right thing at the right time.

Selling a Home in 2026: Why Presentation and Positioning Matter More Than Ever


The process of selling a home in 2026 looks very different than it did even a few years ago. Many markets are experiencing higher inventory, longer decision cycles, and buyers who are far more informed before they ever schedule a showing. Homes are still selling, but they are not selling automatically.

Today’s market rewards preparation and penalizes guesswork. Success is no longer driven by speed alone. It is driven by strategy, clarity, and how well a property is positioned against current competition.

One of the most important changes impacting selling a home in 2026 is buyer selectivity. Buyers have access to more listings, more data, and more price history than ever before. They compare homes side by side online and often make elimination decisions in seconds. If a home does not stand out immediately, it is usually removed from consideration before an in-person showing ever occurs.

This shift has made presentation one of the strongest drivers of activity. Buyers respond to clean, simple, well-maintained homes that feel easy to move into. That does not mean expensive renovations are required. In many cases, homes with major upgrades perform worse than expected because finishes and design choices are too specific.

Instead, buyers gravitate toward homes that are decluttered, bright, neutral, and easy to understand. Clear room purpose, balanced lighting, and overall cleanliness often create more value than new countertops or flooring. When selling a home in 2026, how a property feels matters more than how much money was spent improving it.

Pricing also plays a central role in positioning. One of the biggest mistakes sellers continue to make is pricing high with the intention of adjusting later. In markets with increasing inventory, buyers rarely reward this approach. Overpriced homes tend to receive fewer showings early on, and once momentum is lost, it becomes difficult to regain.

Correct pricing from the beginning creates urgency. It places the home directly within the buyer’s search range and encourages comparison rather than dismissal. When buyers feel a home is priced appropriately, they are more willing to engage, schedule showings, and submit offers. In the context of selling a home in 2026, price is not simply a number, it is a positioning strategy.

Online presentation now determines whether a home is ever seen in person. The majority of buyers decide which homes to tour based entirely on photos, video, and listing clarity. Poor photography, inconsistent lighting, or confusing descriptions create hesitation, even if the home itself is strong.

High-quality images, clean visuals, accurate descriptions, and easy-to-follow layouts dramatically increase engagement. Digital presentation functions as modern curb appeal. If the online experience fails, foot traffic never follows. Anyone focused on selling a home in 2026 must understand that exposure happens digitally first.

Positioning goes beyond pricing and photos. It requires understanding what buyers are comparing and how the home fits into the current inventory landscape. Buyers do not compare listings to last year’s sales. They compare them to what is active today.

Effective positioning answers buyer questions immediately. Why this home instead of another? Why this price? Why now? Homes that communicate those answers clearly attract attention. Homes that do not often blend into the background regardless of quality.

Another important factor in selling a home in 2026 is buyer confidence. Many buyers are cautious, financially aware, and unwilling to stretch beyond what feels comfortable. When a home is poorly presented or incorrectly priced, confidence erodes quickly. Strong presentation and thoughtful positioning remove doubt and make decision-making easier.

Homes that perform well in today’s market share common characteristics. They are priced accurately from the start. They are prepared before listing. They photograph well. They present a clear value story. Most importantly, they launch with intention rather than urgency.

The market will continue to shift, but buyer behavior is unlikely to reverse. People want clarity. They want transparency. And they want to feel confident about what they are purchasing. When those elements are missing, hesitation follows.

For homeowners considering selling a home in 2026, the message is clear. Homes do not sell faster because the market is strong or weak. They sell faster because they are positioned correctly within the market that exists today.

Presentation creates interest. Pricing creates momentum. Positioning creates confidence. When those three elements align, sellers maintain leverage regardless of inventory levels or market headlines. This is what I offer you as my client and more. Contact me for custom packages to suit your needs.

Why Real Estate Timing Matters More Than Waiting for Things to Settle


Every year there is a reason people hesitate to buy or sell a home. Interest rates feel uncertain. Inventory looks tight. Headlines are loud. Elections, global economics, and market forecasts create noise that makes people want to pause.

The most common phrase agents hear is this.
We are just going to wait until things settle.

The problem is that markets rarely settle. They adjust.

In 2026, uncertainty is not new. It is the environment. Waiting for clarity often means waiting forever, and in real estate that usually costs more than taking action with a plan.

Housing markets do not move in straight lines. They respond to supply, demand, consumer behavior, lending conditions, and local pressure. When one factor changes, another reacts. There is no moment where everything becomes calm and predictable.

History shows this clearly. When rates rise, buyers pause. When buyers pause, inventory builds. When rates stabilize even slightly, buyers rush back in at the same time. That rush increases competition almost overnight.

This is why waiting rarely creates opportunity. It often creates congestion.

Buyers who sit on the sidelines hoping for perfect conditions usually face one of two outcomes. Prices move up before they are ready, or the best homes are gone by the time they act. Even in slower markets, desirable properties still sell first. Waiting does not improve selection. It usually shrinks it.

When buyer demand returns, it rarely trickles in. It surges. That is when multiple offers come back, concessions disappear, and affordability tightens again. Many buyers end up paying more not because prices skyrocketed, but because competition removed their leverage.

This cycle repeats because housing is need driven. People still relocate. Families grow. Jobs change. Life continues whether the market feels comfortable or not.

For sellers, waiting can quietly work against them as well.

Many homeowners assume that holding off means selling later for more money. Sometimes that happens. Often it does not.

Inventory shifts quickly. New construction comes online. Neighbors decide to list. Investor activity changes. What looked like a strong seller position can soften without warning.

When more homes hit the market at once, leverage changes. Buyers gain options. Days on market increase. Price reductions become common. Sellers who would have stood out months earlier blend into the crowd.

In real estate, advantage usually belongs to those who move before the shift, not after it becomes obvious.

This is where real estate timing becomes misunderstood.

Most people think timing means guessing the bottom or the top of the market. That is prediction, and prediction is unreliable.

Smart real estate timing is not about being perfect. It is about understanding your position and building a strategy around it.

A buyer with strong financing, flexible closing options, and a clear buy box can succeed in many markets. A seller with pricing strategy, proper exposure, and negotiation planning can protect equity even when conditions change.

The difference is preparation.

Planning allows buyers to move when the right home appears instead of reacting late. Planning allows sellers to enter the market intentionally instead of chasing it.

This is why real estate timing matters more than waiting for headlines to turn positive.

The market does not reward hesitation. It rewards clarity.

When you wait without a plan, you are not standing still. The market continues moving around you. Prices adjust. Inventory shifts. Competition builds quietly in the background.

When you plan, you create options.

You may decide to buy now, later, or not at all. You may choose to sell this year or next. The power comes from understanding the numbers, the local data, and how each decision affects your long term position.

In 2026 especially, consumers are frozen not because opportunities are gone, but because information overload has replaced strategy. The loudest voices focus on what might happen instead of what can be controlled.

Rates will change. Elections will pass. Markets will continue adjusting as they always have.

What rarely changes is this truth.

Waiting for certainty usually increases cost. Planning reduces risk.

Whether buying or selling, success comes from understanding your local market, your financial goals, and your timeline and working with a professional makes all the difference.  


Is Buying an Investment Property with a Sibling a Good Idea?

Buying an investment property with a sibling can be a great way to enter the real estate market, share financial responsibilities, and build wealth together.

However, this decision comes with its own set of challenges and considerations. This article explores the pros and cons of such an arrangement, as well as key factors to consider before making this significant investment.

Benefits of Buying an Investment Property with a Sibling

Shared Financial Burden

One of the most significant advantages of purchasing an investment property with a sibling is the shared financial burden. Splitting the costs of the down payment, mortgage, and maintenance expenses can make real estate investment more accessible.

putting money into investment properties with family.

Additionally, sharing financial responsibilities can ease the pressure and reduce the risk for both parties.

Pooling Resources for a Better Investment

By combining resources, siblings can often afford a higher-quality property or a better location than they could individually. This can lead to higher rental income and appreciation potential.

Pooling resources also allows for more flexibility in choosing investment opportunities that may have been out of reach individually.

Strengthening Family Bonds

Working together on a shared investment can strengthen family bonds. It provides an opportunity for siblings to collaborate, communicate, and achieve common financial goals. This partnership can lead to a more rewarding and supportive relationship.

Potential Challenges of Investing with a Sibling

Differing Financial Goals and Expectations

Siblings may have different financial goals and expectations, which can lead to conflicts. One sibling might prioritize short-term rental income, while the other might focus on long-term appreciation.

These differing priorities can cause friction and disagreements over property management and financial decisions.

For example, one sibling may want to reinvest rental income into property improvements, while the other may prefer to distribute the income as profit.

These differences require careful negotiation and compromise to ensure both parties are satisfied with the investment strategy.

Legal and Financial Complications

Co-owning a property with a sibling introduces legal and financial complexities. It’s essential to establish clear agreements regarding ownership, responsibilities, and exit strategies.

Without proper legal documentation, disputes can arise, leading to potential legal battles and financial strain.

Furthermore, the legal structure of the ownership (e.g., joint tenancy or tenancy in common) can have significant implications for tax liabilities and inheritance issues.

Consulting with a real estate attorney can help navigate these complexities and create a robust legal framework for the partnership.

Personal Conflicts

Personal conflicts can impact the success of the investment. Family dynamics can sometimes interfere with business decisions, leading to emotional stress and tension.

It’s crucial to separate personal feelings from business dealings to maintain a healthy partnership. Regular and open communication, along with setting clear boundaries and expectations, can help manage personal conflicts.

It’s also beneficial to have a conflict resolution plan in place, such as involving a neutral third party to mediate disputes, to ensure that personal issues do not derail the investment.

Key Considerations Before Investing

Clear Communication and Agreement

Clear and open communication is vital when buying an investment property with a sibling. Discuss your financial goals, expectations, and responsibilities in detail.

Establish a written agreement outlining each party’s contributions, decision-making processes, and dispute resolution mechanisms. This clarity can prevent misunderstandings and ensure a smooth partnership.

Legal and Financial Planning

Consult with legal and financial professionals to create a solid partnership agreement. This agreement should cover ownership percentages, profit and loss sharing, decision-making authority, and procedures for selling the property or buying out a sibling’s share.

Proper planning can help avoid future conflicts and protect both parties’ interests.

Financial Readiness and Stability

Assess your financial readiness and stability before investing. Ensure that both siblings have a stable income, good credit scores, and sufficient savings for the down payment and ongoing expenses.

Financial stability is crucial for managing unexpected costs and maintaining the property.

Exit Strategy

Plan an exit strategy in case one sibling wants to sell their share or if the investment doesn’t go as planned. Outline the steps for buying out a sibling’s share or selling the property. Having a clear exit strategy can prevent disputes and ensure a smooth transition if circumstances change.

Managing the Investment Property

Division of Responsibilities

Clearly define the division of responsibilities for managing the property. Decide who will handle tasks such as finding tenants, collecting rent, maintaining the property, and dealing with repairs. Assigning specific roles can streamline operations and prevent conflicts over duties.

Regular Meetings and Updates

Hold regular meetings to discuss the property’s performance, financial status, and any issues that arise. Regular communication helps keep both parties informed and engaged in the investment. It also provides an opportunity to address any concerns and make necessary adjustments.

Hiring Professional Management

Consider hiring a professional property management company if neither sibling has the time or expertise to manage the property effectively. A property manager can handle day-to-day operations, tenant relations, and maintenance, allowing siblings to focus on their primary jobs or other responsibilities.

Conclusion

Buying an investment property with a sibling can be a rewarding venture, offering shared financial burdens, pooled resources, and strengthened family bonds.

However, it also comes with potential challenges, such as differing financial goals, legal complications, and personal conflicts. Clear communication, legal and financial planning, and regular management are crucial for a successful partnership.

By carefully considering these factors, siblings can make a wise investment and build a prosperous future together.

Seasonal Benefits of Buying a Home in the Winter

Winter may not be the traditional season for buying a home, but it offers a host of advantages that can make it a smart choice for many buyers.

With lower competition, motivated sellers, and potential financial benefits, purchasing a home in the winter can be both strategic and cost-effective. Let’s explore the seasonal benefits of buying a home in the winter and why it might be the perfect time for you to make your move.

Lower Competition and Fewer Buyers

One of the most significant benefits of buying a home in the winter is the reduced competition. Many buyers prefer to wait until spring or summer, leading to fewer people competing for the same properties.

This lower competition can translate into less pressure and a smoother buying process.

More Time to Decide

Thorough Evaluation and Informed Decision Making

With fewer buyers, you won’t feel rushed to make quick decisions. You can take your time to thoroughly evaluate properties, weigh the pros and cons, and make a more informed decision.

Happy family lying on floor after buying new houseThis slower pace can be particularly beneficial for first-time homebuyers, who might need extra time to understand the market and make a confident choice.
Motivated Sellers and Potential for Better Prices

Winter sellers often have compelling reasons for listing their homes, such as job relocations or financial imperatives, which can make them more eager to negotiate on price and terms.

Homes on the market during winter may be priced more competitively to facilitate quicker sales. This creates a favorable environment for buyers to secure better deals and potentially save on their home purchases compared to peak seasons with more aggressive pricing.

Attractive Pricing and Negotiation Opportunities

Winter sellers often have compelling reasons for listing their homes, such as job relocations or financial imperatives, which can make them more eager to negotiate on price and terms.

Homes on the market during the winter may be priced more competitively to facilitate quicker sales. This creates a favorable environment for buyers to secure better deals and potentially save on their home purchase compared to peak seasons with more aggressive pricing.

Financial Benefits and Year-End Incentives

Winter coincides with the end of the fiscal year, and many financial institutions are eager to close deals to meet their annual targets. This can result in better mortgage rates, discounts, and incentives for buyers.

Real estate agents and brokers might also be more flexible with their fees to secure deals before the year ends.

Tax Advantages and Savings Opportunities

Purchasing a home before the year ends can offer tax benefits. You can deduct mortgage interest, property taxes, and some closing costs on your annual tax return.

These deductions can lead to significant savings, making winter home buying not only strategic but also financially beneficial.

Easier to Identify Issues with the Property

Assessing Insulation, Heating Efficiency, and Overall Condition

Winter is an ideal time to assess a home’s insulation and heating efficiency. During a home inspection, you can easily identify drafts, cold spots, and other issues that might not be as apparent in warmer months.

This can help you ensure the home is energy-efficient and comfortable during the colder season.

Evaluating Weather-Related Resilience

Winter weather provides a unique opportunity to see how a home withstands harsh conditions.

You can observe the state of the roof, gutters, and drainage systems during rain or snow. This firsthand experience can reveal potential maintenance issues and help you make a more informed decision about the property’s resilience and durability.

Real Estate Market Trends

Understanding Seasonal Market Fluctuations and Benefits of Buying a Home in the Winter

The real estate market experiences predictable seasonal fluctuations, with winter typically being a quieter period characterized by reduced transaction volumes.

This seasonal trend can work in favor of buyers looking for specific types of properties or seeking opportunities in their desired neighborhoods.

Understanding these market dynamics, including the benefits of buying a home in the winter, empowers buyers to strategically time their purchases for maximum advantage.

Long-Term Market Considerations

While winter may be slower in terms of market activity, it presents favorable conditions for long-term investment strategies and highlights the benefits of buying a home in the winter.

Real estate traditionally appreciates over time, and purchasing during the off-season positions buyers to benefit from future property value appreciation.

Down trend housing market concept. Financial data on the background.

Moreover, winter often unveils unique property listings that may not be available or as accessible during more competitive seasons, offering buyers a broader selection to choose from.

Conclusion

There are a number of benefits to buying a home in the winter, from lower competition and motivated sellers to financial incentives and the ability to spot potential issues.

By understanding these advantages, you can make a strategic decision that aligns with your goals and budget. Don’t wait for spring—your dream home might be waiting for you this winter.

FAQs

Is it cheaper to buy a home in the winter?

Yes, it can be cheaper to buy a home in the winter due to several factors. Firstly, there is typically lower competition among buyers during the winter months, which can drive prices down or make sellers more willing to negotiate.

Additionally, motivated sellers who list their homes in the winter may be more inclined to accept lower offers to facilitate a quicker sale. These factors combined can lead to cost savings for buyers compared to more competitive seasons like spring and summer.

What are the risks of buying a home in the winter?

Buying a home in the winter does come with some risks. One of the main challenges is weather-related issues during the moving process. Cold temperatures, snow, and ice can make moving logistics more complicated and potentially hazardous.

Another risk is the difficulty in assessing the landscaping and exterior features of the property, such as the condition of the yard, driveway, and outdoor structures, which may be covered in snow or dormant during the winter.

How can the winter weather help identify home issues?

Winter weather provides a unique opportunity to uncover specific issues that may not be as noticeable during warmer seasons.

For example, cold temperatures can reveal insulation problems or drafts in the home. Heating systems are put to the test during winter, allowing buyers to assess their efficiency and performance.

Additionally, snow and ice can highlight drainage issues, roof conditions, and the overall resilience of the property to harsh weather conditions.

Are mortgage rates lower in the winter?

Yes, mortgage rates can be more competitive in the winter months. Financial institutions often have year-end targets to meet, prompting them to offer attractive rates and incentives to borrowers.

This competitive environment can benefit buyers by providing access to lower interest rates, potentially reducing overall borrowing costs when purchasing a home in the winter.

What are the tax benefits of buying a home in the winter?

Buying a home before the year ends can offer several tax advantages. Buyers may be eligible to deduct mortgage interest payments, property taxes, and certain closing costs on their annual tax returns for the year of purchase.

These deductions can result in significant tax savings, making winter home buying not only financially advantageous but also tax-efficient.

The Ultimate Checklist for Buying a Fixer Upper

Buying a fixer upper can be an exciting adventure and a great investment opportunity. However, it requires careful planning and consideration. Here’s the ultimate checklist to ensure you make a smart purchase and transform your fixer upper into your dream home.

1. Assess Your Budget

Before diving into the process, it’s crucial to know your financial limits. This includes the purchase price of the home and the renovation costs. Factor in a buffer for unexpected expenses that often arise during renovations. A pre-approved mortgage gives you a clear picture of how much you can borrow and shows sellers that you are a serious buyer.

Estimate All Costs

When assessing your budget, don’t forget to include costs such as closing fees, insurance, property taxes, and contingencies for unexpected repairs. Being thorough ensures you won’t face financial strain mid-project.

Real estate services cost. House insurance protection and safety. moving and relocation. house frame in green residential area with money purse. Downsizing. Loan for new home. Finding new property
 

Financing Options

Explore different financing options, like renovation loans or home equity lines of credit. These can provide the necessary funds to cover both the purchase and renovation costs, spreading payments over time.

Return on Investment

Consider the potential return on investment (ROI). Research comparable properties in the area to estimate the future market value of the renovated home. This will help determine if the fixer upper is a wise financial decision. Additionally, it’s crucial to factor in the current market trends and potential future developments in the neighborhood.

Are there any upcoming infrastructure projects, like new schools, parks, or commercial centers? These can significantly boost property values and make your investment more profitable. Consulting with a local real estate agent can provide valuable insights into the area’s growth prospects and help you make an informed decision. Balancing your budget with these future potential gains can ensure you make a sound financial decision.

2. Conduct a Thorough Inspection

A comprehensive inspection is a must when buying a fixer upper. Hire a professional inspector to assess the structural integrity, plumbing, electrical systems, roof, foundation, and other critical components. Create a detailed list of repairs and renovations required, categorizing them into must-do repairs and optional upgrades.

Building inspection, male inspecting home, reconstructed construction, renovation or check defect, before finish handing it over to client, customer. Engineering worker.
 

Identify Major Issues

Focus on identifying major issues such as structural damage, roofing problems, and outdated electrical systems. These can be costly and essential to address before moving forward with aesthetic improvements.

DIY vs. Professional Help

Decide which projects you can tackle yourself and which ones require professional help. DIY projects can save money, but certain tasks, like electrical and plumbing work, are best left to licensed professionals.

3. Calculate Renovation Costs

Obtain estimates from multiple contractors for the necessary renovations. This will give you a realistic idea of the costs involved and help you compare different options. If you plan to handle some projects yourself, factor in the cost of materials and tools, being realistic about your skills and the time commitment required.

Budget for Overruns

Always budget for overruns. Unexpected issues can and do arise, and having a financial cushion ensures that these surprises don’t derail your renovation plans.

Prioritize Key Areas

Address any structural issues first, such as foundation problems, roof leaks, or plumbing issues. These are essential for the safety and stability of the home. Prioritize upgrades to essential systems like electrical wiring, plumbing, and HVAC to ensure these systems are up to code and functioning properly.

4. Plan for Permits and Regulations

Check local building codes and regulations to ensure your renovation plans comply. This can prevent costly fines and delays. Depending on the scope of your renovations, you may need various permits. Apply for these in advance to avoid any interruptions to your project.

Permit Requirements

Understand which renovations require permits. Common projects that need permits include structural changes, electrical upgrades, and major plumbing work. Complying with local regulations is crucial for safety and legality.

Navigating Local Codes

Different municipalities have different building codes. It’s essential to familiarize yourself with the specific requirements in your area. Consulting with a local contractor or inspector can help you navigate these regulations efficiently.

5. Prioritize Key Areas

Address any structural issues first, such as foundation problems, roof leaks, or plumbing issues. These are essential for the safety and stability of the home. Prioritize upgrades to essential systems like electrical wiring, plumbing, and HVAC to ensure these systems are up to code and functioning properly.

Cosmetic Improvements

After addressing structural and system issues, focus on cosmetic improvements like painting, flooring, and landscaping. These enhance the home’s appeal and can significantly boost its value.

Energy Efficiency

Consider incorporating energy-efficient upgrades. Installing insulation, energy-efficient windows, and appliances can reduce future utility costs and make the home more attractive to buyers if you decide to sell.

Landscape Design

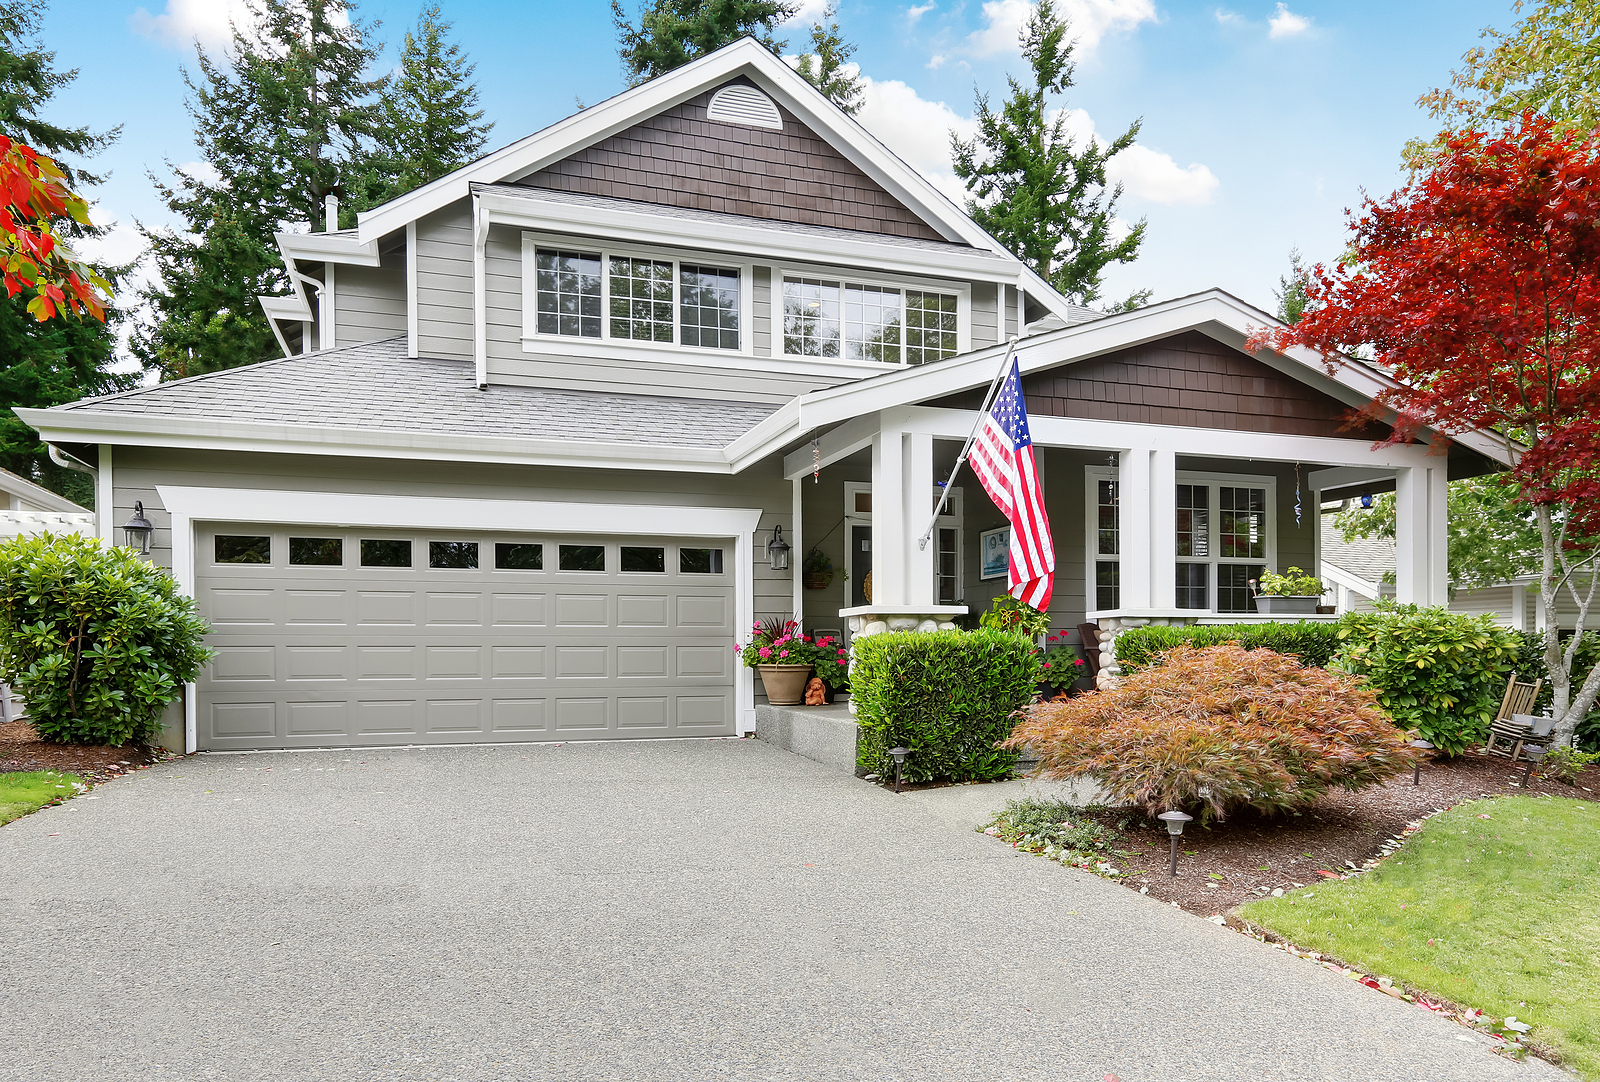
Nice curb appeal of grey house with garage and driveway. Column porch with American flag. Northwest USA
 

Don’t overlook the exterior of the home. A well-designed landscape can add curb appeal and create a welcoming environment. Simple additions like new plants, a fresh lawn, and updated walkways can make a significant difference.

6. Create a Renovation Timeline

A detailed renovation timeline helps keep your project on track. Outline each phase of the renovation, setting realistic deadlines for each task. This will help manage expectations and ensure a smooth workflow.

Setting Realistic Deadlines

Consider the scope of each renovation task when setting deadlines. Some projects, like plumbing or electrical work, may take longer due to their complexity. Build in buffer time for unexpected delays.

Hiring the Right Professionals

Finding reliable contractors is crucial for staying on schedule. Do thorough research, read reviews, and get recommendations from friends or family. A good contractor can make a significant difference in the quality and timing of your renovations.

Regular Progress Check-Ins

Schedule regular check-ins with your contractors to monitor progress. This helps catch any issues early and ensures that the project stays on track. Being proactive can prevent small problems from becoming major setbacks.

7. Finalize the Purchase

Once you have a clear understanding of the budget, necessary repairs, and renovation costs, you can proceed with the purchase. Work closely with your real estate agent to negotiate the best deal and ensure all legal paperwork is in order.

Closing the Deal

During the closing process, review all documents carefully. Ensure that the terms are as agreed and there are no hidden clauses. It’s also wise to have a lawyer review the contract to protect your interests.

Post-Purchase Steps

After closing, start with the most critical repairs. Prioritize safety and structural integrity before moving on to cosmetic upgrades. A well-planned approach ensures a successful renovation journey.

Conclusion

Buying a fixer upper is a rewarding journey that can lead to significant financial and personal rewards. By following this ultimate checklist, you can navigate the complexities of purchasing and renovating a fixer upper, transforming it into your dream home.

Remember to stay organized, be prepared for surprises, and enjoy the process of creating a space that reflects your style and needs.

Investment Potential: Attached vs Detached Family Homes

Understanding the investment potential of attached versus detached family homes is crucial for prospective homeowners and real estate investors. This article explores key factors influencing investment decisions and compares the advantages of each property type.

Definitions

Definition of Attached Family Homes

Attached family homes, like townhouses or row houses, share one or more walls with neighboring properties. They are typically found in urban or suburban areas and offer a balance between apartment living and detached homes.

Definition of Detached Family Homes

Recently built townhomes.

Detached family homes are standalone properties with no shared walls. They often feature larger plots of land, providing more privacy and outdoor space. Detached homes are common in suburban and rural settings.

Investment Considerations

Initial Cost and Affordability

Attached homes generally have a lower initial cost due to shared construction expenses and smaller land plots. This affordability makes them appealing to first-time buyers and investors with limited budgets.

Maintenance Costs and Responsibilities

Maintenance costs for attached homes may be lower as exterior upkeep is often managed by homeowners’ associations (HOAs). In contrast, owners of detached homes are responsible for all maintenance, including landscaping.

Appreciation Potential

Detached homes typically appreciate faster due to their larger land sizes and greater privacy. However, well-located attached homes in desirable urban areas can also see significant appreciation over time.

Rental Income Potential

Red For Rent Real Estate Sign in Front of Beautiful House.

Detached homes often command higher rental rates due to their larger size and privacy. Attached homes, especially those in urban locations, can still generate substantial rental income if well-maintained and equipped with modern amenities.

Market Trends

Current Market Trends

Attached homes are increasingly popular in urban areas where land is scarce and demand for affordable housing is high. Detached homes remain strong in suburban and rural markets, appealing to families seeking more space.

Historical Market Performance

Both attached and detached homes have historically shown steady appreciation. Detached homes typically have a longer track record of higher appreciation rates due to land value.

Location and Environment

Urban vs Suburban Preferences

Attached homes are prevalent in urban areas due to their compact size and proximity to city centers. Detached homes are preferred in suburban and rural areas for their larger lots and quieter surroundings.

Impact of Location on Property Value

Proximity to amenities such as schools, shopping centers, and public transit influences property values for both attached and detached homes. Urban attached homes and suburban detached homes can both command premium prices based on location.

Cafe and Neighborhood Isometric. Set of very detailed isometric vector

Neighborhood and Community Impact

A well-maintained neighborhood with good schools and services enhances property values for both attached and detached homes. Community amenities play a crucial role in attracting buyers and tenants.

Privacy and Lifestyle

Privacy Levels

Detached homes offer greater privacy as they are standalone properties with no shared walls. Attached homes, while offering some privacy measures, involve closer proximity to neighbors.

Lifestyle Preferences

Buyers choosing between attached and detached homes often prioritize lifestyle preferences. Those valuing convenience and community may prefer attached homes, while those prioritizing space and privacy lean towards detached homes.

Security and Safety

Security Considerations

Attached homes may benefit from shared security measures in community settings, while detached homes allow for more personalized security installations such as fences and comprehensive alarm systems.

Safety Features

Both attached and detached homes benefit from local safety services like police and fire departments. Community safety measures can enhance property desirability and resale value.

Financing and Tax

Financing Options

Financing options are similar for both attached and detached homes, with factors such as location and market demand influencing loan approval and terms.

Tax Implications

Property taxes, mortgage interest deductions, and potential capital gains taxes apply to both property types. Buyers should consider these financial factors when evaluating investment potential.

Resale Value and Marketability

Factors Affecting Resale Value

Resale value for both attached and detached homes is influenced by factors such as location, property condition, and market trends. Well-maintained homes in desirable neighborhoods tend to retain or increase in value.

Marketability

Buyer preferences and market conditions dictate how quickly homes sell. Urban attached homes and suburban detached homes each cater to different buyer demographics, affecting marketability.

Expert Insights

Real Estate Agent Perspectives

Real estate agents offer insights on market trends, buyer preferences, and investment strategies for attached versus detached homes.

Financial Advisor Insights

Financial advisors provide guidance on evaluating investment opportunities in real estate and maximizing returns based on individual financial goals.

 Common Questions About Attached Homes

  1. What are the typical advantages of buying an attached home?

    • Attached homes often offer lower purchase prices compared to detached homes, making them more affordable for buyers. They also tend to have shared maintenance responsibilities, which can reduce individual upkeep costs.
  2. What are the potential drawbacks of living in an attached home?

    • One common drawback is reduced privacy due to shared walls with neighbors. Noise from adjoining units can also be a concern, depending on the construction and soundproofing of the property.
  3. Are there any specific financing considerations for attached homes?

    • Financing options for attached homes are similar to those for detached homes. However, some lenders may have specific requirements based on the property’s location, condition, and HOA regulations.

Common Questions About Detached Homes

  1. What are the primary benefits of purchasing a detached home?

    • Detached homes offer more privacy and space compared to attached homes. They often come with larger yards or outdoor areas, providing homeowners with more room for personalization and outdoor activities.
  2. What should buyers consider regarding maintenance costs for detached homes?

    • Owners of detached homes are responsible for all maintenance, including exterior upkeep and landscaping. While this can require more effort and expense compared to attached homes, it also allows for greater control over property maintenance decisions.

Conclusion

Summary

Choosing between attached and detached homes involves weighing financial considerations, lifestyle preferences, and market trends. Both property types offer unique advantages, appealing to different segments of buyers and investors.

Final Thoughts

Ultimately, the decision to invest in attached or detached homes hinges on individual priorities and long-term investment objectives. Consulting with real estate professionals can provide further clarity and guidance.

Call to Action

For personalized advice on real estate investments or to explore current market opportunities, contact a trusted real estate advisor or financial planner.

Steps on How to Invest in Vacation Property Wisely

Investing in vacation properties can be a lucrative and enjoyable way to build wealth. However, it requires careful planning and consideration to ensure that you make wise decisions.

This article will guide you through the essential steps on how to invest in vacation property wisely.

Understanding the Vacation Property Market

Researching Market Trends

Before diving into any investment, it’s crucial to understand the current market trends. Look into popular vacation destinations, occupancy rates, and property values.

Understanding these trends will help you make informed decisions and avoid potential pitfalls.

Consider seasonal variations as well; some areas may have high tourist activity in specific seasons, which can impact rental income predictably.

Evaluating Potential Locations

Location is everything in real estate, especially when it comes to vacation properties.

Evaluate various locations based on their popularity, accessibility, amenities, and future development plans.

Opt for locations that have a steady influx of tourists and a high demand for rentals. Research local attractions, the climate, and the overall appeal of the area to tourists.

Areas with consistent demand throughout the year, such as beach towns, ski resorts, or cultural hotspots, often offer better returns on investment.

Financial Planning and Budgeting

Assessing Your Financial Situation

Determine your budget and financial readiness before investing. Consider your savings, income, credit score, and potential loan options.

It’s essential to have a clear understanding of your financial health to avoid overextending yourself. Speak with a financial advisor to understand the implications of taking on additional debt and how it fits into your overall financial strategy.

Calculating Costs and Potential ROI

Investing in vacation properties involves various costs, such as the purchase price, taxes, maintenance, and management fees.

Calculate these costs and compare them to the potential rental income to determine your return on investment (ROI). Use conservative estimates to avoid unrealistic expectations.

Additionally, consider the cost of furnishing the property to a standard that will attract renters. High-quality furnishings can justify higher rental rates but will also require a larger upfront investment.

Choosing the Right Property

Identifying Key Property Features

When selecting a vacation property, consider features that appeal to renters. These may include proximity to attractions, scenic views, amenities like pools or hot tubs, and spacious layouts.

The more appealing the property, the higher the occupancy rate you can expect. Properties with unique or luxurious features, such as private beach access or panoramic views, can often command higher rental rates and increase your return on investment.

Inspecting the Property

Always conduct a thorough inspection of the property before purchasing. Hire a professional inspector to check for structural issues, plumbing, electrical systems, and any potential repairs.

This step will help you avoid unexpected expenses and ensure the property is in good condition. An inspector can also provide an estimate for necessary repairs, which can be a critical factor in your decision-making process.

It’s important to factor these potential costs into your overall budget.

Managing the Investment

Hiring a Property Manager

Managing a vacation property can be time-consuming, especially if you don’t live nearby. Consider hiring a property management company to handle bookings, maintenance, and guest communications.

A good property manager can significantly enhance your investment’s performance. They can also ensure that your property remains well-maintained, handle emergencies, and provide local knowledge that can be invaluable for attracting and retaining guests.

Marketing and Advertising

Effective marketing is crucial for attracting renters. Utilize various platforms like Airbnb, Vrbo, and social media to promote your property. High-quality photos, engaging descriptions, and competitive pricing will help you stand out in a crowded market.

Additionally, consider creating a dedicated website for your property to provide more detailed information and facilitate direct bookings. Offering virtual tours and highlighting unique features of the property can also attract more interest.

Leveraging Instagram’s Strategies

Instagram can be a powerful tool for marketing your vacation property. Use visually appealing photos and videos to showcase the best aspects of your property. Engage with potential guests by using relevant hashtags, running promotions, and collaborating with travel influencers.

Instagram Stories and Reels can also provide dynamic content that captures the attention of potential renters.

Legal Considerations and Compliance

Understanding Local Regulations

Different locations have varying regulations regarding vacation rentals. Ensure you understand and comply with local laws, zoning restrictions, and licensing requirements. Non-compliance can result in fines or legal issues that can jeopardize your investment.

Some areas may have strict short-term rental laws or require special permits and licenses. It’s crucial to stay informed about these regulations and keep up with any changes.

Insurance and Liability

Protect your investment with the appropriate insurance coverage. Vacation rental insurance typically covers property damage, liability, and loss of income due to cancellations.

Consult with an insurance agent to find a policy that suits your needs. Additionally, consider including a liability waiver in your rental agreements to protect yourself from potential legal issues arising from guest injuries or damages.

Tax Implications

Investing in vacation properties can have various tax implications. Understand the tax benefits and obligations associated with owning a rental property.

For instance, you may be able to deduct mortgage interest, property taxes, and certain expenses related to the maintenance and management of the property. Consult with a tax professional to ensure you take full advantage of any tax benefits and comply with all tax laws.

Conclusion

Investing in vacation property wisely involves thorough research, financial planning, and effective management. By understanding the market, choosing the right property, and complying with legal requirements, you can maximize your returns and enjoy the benefits of owning a vacation rental.

Remember, a successful investment requires ongoing attention and adaptation to changing market conditions.

FAQs

1. What is the best location to invest in vacation property?

The best location depends on factors such as tourist demand, accessibility, and amenities. Popular destinations with year-round appeal tend to be good investments. Researching local attractions and seasonal trends can help identify high-potential areas.

2. How much should I budget for maintenance costs?

Maintenance costs can vary, but it’s wise to budget around 1-2% of the property’s value annually for upkeep and repairs. This estimate includes routine maintenance and potential unexpected repairs.

3. Do I need a property manager for my vacation rental?

While not mandatory, hiring a property manager can help handle day-to-day operations, especially if you don’t live near the property or have limited time. A property manager can also improve guest satisfaction and manage emergency situations effectively.

4. What type of insurance do I need for a vacation property?

Vacation rental insurance, which covers property damage, liability, and income loss, is essential. Consult with an insurance agent to choose the right coverage. This insurance is specifically designed to address the unique risks associated with short-term rentals.

5. How can I ensure high occupancy rates for my vacation rental?

High occupancy rates can be achieved through effective marketing, competitive pricing, and providing excellent guest experiences. Utilizing multiple booking platforms and maintaining positive reviews are also beneficial. Offering amenities and personalized touches can enhance guest satisfaction and encourage repeat bookings.

6. What are the risks of investing in vacation properties?

Risks include market fluctuations, regulatory changes, and unexpected maintenance costs. Proper research and financial planning can help mitigate these risks. Staying informed about local market conditions and maintaining a financial cushion for emergencies can provide additional security.


Finding Your Dream Home: Which Home Type is Perfect for You?

Finding your dream home is an exciting journey filled with important decisions. The type of home you choose significantly impacts your lifestyle, finances, and long-term happiness.

In this article, we’ll explore different home types, weigh their pros and cons, and help you determine which home type is perfect for you.

Understanding Different Home Types

Single-Family Homes

Single-family homes are standalone residences, offering privacy and space. They typically come with a yard and provide ample room for families.

family home in urban neighborhood
 

Pros:

  • Privacy: No shared walls, giving you complete control over your living space.
  • Space: Often larger, making them ideal for families or those who need extra room.
  • Customization: Freedom to modify the home and property as you please.

Cons:

  • Maintenance: All upkeep, including lawn care and repairs, falls on you.
  • Cost: Generally more expensive to purchase and maintain compared to other home types.

Condominiums (Condos)

Condos are individual units within a larger building or complex, sharing common areas and amenities.

Pros:

  • Amenities: Access to shared facilities like gyms, pools, and security services.
  • Maintenance: Exterior maintenance and common areas are managed by the condo association.
  • Affordability: Often more affordable than single-family homes.

Cons:

  • HOA Fees: Monthly fees for maintenance and amenities can add up.
  • Limited Control: Restrictions on modifications and rules set by the condo association.
  • Privacy: Shared walls and common areas can reduce privacy.

Townhouses

Townhouses are multi-story homes sharing one or two walls with adjacent properties, combining aspects of both condos and single-family homes.

Row of colorful red yellow blue white green painted residential townhouses homes houses with brick patio gardens in summer
 

Pros:

  • Affordability: Generally less expensive than single-family homes.
  • Space: More spacious than condos, with multiple floors and often a small yard.
  • Community: Often part of planned communities with shared amenities.

Cons:

  • HOA Fees: Like condos, townhouses often come with association fees.
  • Noise: Shared walls can lead to noise from neighbors.
  • Limited Yard: Smaller outdoor space compared to single-family homes.

Apartments

Apartments are rental units within larger buildings or complexes, typically managed by a landlord or property management company.

Pros:

  • Flexibility: Short-term leases and the ability to move without selling.
  • Maintenance: All repairs and upkeep are handled by the landlord.
  • Affordability: No need for a large down payment, making it easier to budget.

Cons:

  • No Equity: Rent payments do not build equity or ownership.
  • Restrictions: Limited ability to make changes or personalize the space.
  • Noise: Shared walls and common areas can lead to noise disturbances.

Factors to Consider When Choosing a Home Type

Lifestyle Needs

Your lifestyle plays a crucial role in determining the best home type. Consider factors such as family size, work-from-home needs, and recreational preferences.

  • Families: Single-family homes and townhouses offer more space and privacy, making them ideal for families with children.
  • Professionals: Condos and apartments may be more suitable for busy professionals who prioritize location and amenities over space.
  • Retirees: Condos and single-story townhouses provide easy maintenance and accessibility.

Budget and Financial Goals

Evaluate your budget and long-term financial goals when choosing a home type. Consider the initial purchase cost, ongoing maintenance expenses, and potential for property value appreciation.

  • First-Time Buyers: Condos and townhouses can be more affordable options for first-time buyers.
  • Investors: Single-family homes often appreciate in value more than other home types, making them a better investment.
  • Renters: Apartments offer flexibility and lower upfront costs but do not build equity.

Maintenance and Upkeep

Consider how much time and effort you’re willing to invest in home maintenance. Single-family homes require more upkeep, while condos and apartments offer low-maintenance living.

  • Busy Individuals: Condos and apartments are ideal for those who prefer minimal maintenance responsibilities.
  • DIY Enthusiasts: Single-family homes and townhouses provide opportunities for home improvement projects and landscaping.

Making the Final Decision

Weighing the Pros and Cons

Create a list of pros and cons for each home type based on your personal preferences, lifestyle needs, and financial situation. This can help clarify which home type aligns best with your priorities.

Visiting Different Home Types

Visit a variety of homes to get a feel for what each type offers. Open houses and tours can provide valuable insights into the layout, community, and overall vibe of different properties.

happy young couple buying new home with real estate agent and looking big comfort bright apartment plans and taking key
 

Seeking Professional Advice

Consult with a real estate agent to gain expert advice on the best home type for your needs. Agents can offer valuable market insights, help you navigate the buying process, and ensure you find a home that meets your criteria.

Conclusion

Finding your dream home is a significant milestone, and choosing the right home type is a crucial step in this journey.

By understanding the different home types, considering your lifestyle and financial goals, and seeking professional advice, you can make an informed decision that leads to long-term happiness and satisfaction.


FAQs

1. What are the main differences between a condo and a townhouse?

Condos are individual units within a larger building with shared common areas, while townhouses are multi-story homes sharing walls with adjacent properties but offering more space and sometimes a small yard.

2. How do HOA fees impact the cost of living in a condo or townhouse?

HOA fees cover maintenance of common areas and amenities but can be a significant monthly expense. It’s important to factor these fees into your overall budget.

3. What should I consider when choosing between buying and renting?

Consider your long-term goals, financial situation, and lifestyle needs. Buying builds equity and offers stability, while renting provides flexibility and lowers upfront costs.

4. Are single-family homes a better investment than condos?

Single-family homes often appreciate more in value, making them a better long-term investment. However, condos can be more affordable and offer desirable amenities.

5. How can I determine which home type is best for my lifestyle?

Evaluate your lifestyle needs, budget, and willingness to handle maintenance. Visit different home types and consult with a real estate agent to make an informed decision.

s1