The Monthly Payment Is Not the Whole Payment

A lot of buyers do the same thing at the beginning of the search.

They look at the list price, run a mortgage calculator, get a rough monthly number, and decide whether the house feels possible from there.

That is understandable. It is also where a lot of people get themselves in trouble.

Because the monthly payment is not the whole payment.
The mortgage matters, obviously, but it is only one part of what it costs to own a home. Buyers who stop at principal and interest usually end up surprised later by how much more the real number actually is. The Consumer Financial Protection Bureau makes this point very directly. Your total monthly home payment can include principal, interest, property taxes, mortgage insurance, homeowner’s insurance, supplemental insurance like flood insurance, and homeowners’ association fees, and some of those costs can rise over time.

That is the part buyers need to understand before they fall in love with a house.

Recently built townhomes.

In June 2026, the average 30-year fixed mortgage rate is still sitting around 6.49%, according to Freddie Mac. That means the mortgage payment is already doing a lot of work in most household budgets before you add everything else. When rates are this high, small differences in total monthly cost matter more, not less.

This is why the monthly payment is not the whole payment is such an important conversation right now. Buyers are not just deciding whether they can get approved. They are deciding whether the full cost of ownership fits their life in a way that still feels manageable six months after closing.

Property taxes are one place buyers get caught off guard. Depending on the market, taxes can add a meaningful amount to the monthly number, and they are not something you can wish away after the offer is accepted. Insurance is another one. That has become an even bigger issue in recent years as insurance costs have climbed, especially in places with higher climate risk. A U.S. Treasury Department study reported in early 2025 found that homeowners in the highest-risk areas paid average annual premiums of $2,321, which was 82% higher than homeowners in the lowest-risk areas.

That matters because buyers often underestimate insurance by using a rough placeholder that looks harmless in an online calculator. Then the real quote comes in and the monthly payment changes in a way that is not small at all.

HOA fees and supplemental insurance create the same problem. Some buyers barely factor them in at the start, then realize later that the home they thought they could comfortably afford carries another few hundred dollars a month in obligations that were not fully part of the conversation. The CFPB specifically warns buyers to account for HOA dues, insurance, taxes, and maintenance rather than treating the mortgage as the only real cost.

Then there is maintenance, which is not part of your lender’s approval but absolutely is part of real life.
A lot of buyers focus so hard on getting into the house that they forget the house will keep costing money after they own it. Something breaks. Something ages out. Something needs to be serviced, cleaned, replaced, or repaired. The CFPB’s homebuyer checklist explicitly tells buyers to leave room for repairs, improvements, moving costs, and other ownership expenses, which is advice that sounds basic until you meet someone who emptied every available dollar into closing and then got hit with a repair in month two.

That is why the monthly payment is not the whole payment should be part of every serious buying conversation. A home can look affordable in a calculator and still feel tight in real life once taxes, insurance, HOA fees, utilities, and maintenance start stacking up.

This is also where buyers need to separate approval from comfort.

A lender may approve one number. That does not automatically mean that number fits your life well. Freddie Mac has pointed out that borrowers who shop around with multiple lenders can save real money, which is a good reminder that even the financing itself should not be treated as a one-number decision. Approval is one piece. Affordability is broader than that.

The buyers who usually feel strongest after closing are not always the ones who bought the biggest house or stretched the farthest. They are usually the ones who understood the real cost before they bought. They knew what their full monthly number looked like. They knew where the pressure points were. They built in room for life instead of spending every dollar just to win the deal.
That is the smarter approach in this market.

Reuters reported in June that economists still expect the housing market to stay subdued while mortgage rates remain above 6%, and that the average mortgage payment is now consuming a large share of median after-tax income. That makes it even more important for buyers to stop treating affordability like a rough estimate and start treating it like the central decision.

Because once the keys are in your hand, the list price stops mattering.

What matters then is whether the house still fits your life when the real bills start arriving.

That is the number worth paying attention to.

Why Smaller Homes Are Winning Right Now

For a long time, bigger felt like the goal.

More square footage meant more success, more flexibility, more room to grow, and more house for the money. That mindset is still out there, but it is not driving buyers the way it used to. More people are looking at housing through a different lens now. They are not asking how much house they can stretch into. They are asking what kind of house actually fits the life they have and the budget they want to protect.

That is a big reason smaller homes are winning right now.

Affordability has forced buyers to get more honest. Harvard’s Joint Center for Housing Studies reported that homebuilders have already been responding to affordability pressure by delivering smaller homes, with the median size of a new single-family home falling for the third straight year in 2024 to 2,150 square feet. The same report noted a sharp increase in townhome construction, which makes sense because smaller homes and attached products tend to hit a more realistic price point for buyers trying to make the monthly numbers work.

That shift is not just about price. It is also about how people want to live.

A large house sounds great until you have to pay to heat it, cool it, furnish it, clean it, insure it, and maintain it. Extra square footage has a way of looking impressive in a listing and a lot less impressive when the utility bills show up or when every spare room turns into a catch-all for things nobody really needs. Buyers are more aware of that now than they were a few years ago, especially after a long stretch of high prices, high borrowing costs, and generally expensive everything.

Freddie Mac made this point pretty directly in its affordability research. It found that buyers are adapting to weaker affordability by targeting smaller homes than they did in the past. That is a practical response, not a trend for trend’s sake. When buyers are trying to stay within a payment they can actually live with, smaller homes start looking a lot smarter.

That matters because the conversation is no longer just about whether a buyer qualifies. It is about whether the home feels sustainable after closing.

A smaller home often gives buyers more breathing room. It can mean a lower purchase price, less pressure on the monthly payment, lower maintenance, and fewer expensive surprises hiding inside unused space. It can also mean buyers are not spending the next several years financially pinned down by a house that looked good on paper but feels heavy in real life.

That is one of the biggest reasons smaller homes are winning right now. They are not always the dream buyers thought they wanted five or ten years ago, but they often make more sense once the full cost of ownership gets real.

Real estate services. House insurance protection and safety. moving and relocation. Small house within bigger house frame in green residential area. Downsizing. Loan for new home. Finding new property

There is also a lifestyle shift happening underneath all of this. Buyers are paying much more attention to function than they used to. They care less about having rooms that sound impressive and more about having spaces they will actually use. A well-designed smaller home can live much better than a larger one with awkward flow, wasted rooms, or square footage that never really serves a purpose.

That kind of practical thinking is showing up across the market. Harvard’s rental housing research found that affordability pressure remains intense even though rent growth has cooled in many places, which reinforces the bigger picture. People are more cost-conscious, more selective, and less interested in housing that stretches them just because it sounds aspirational.

Smaller homes are also benefiting from a simple truth buyers sometimes forget when they are scrolling online. A house does not need to be large to feel good. It needs to work. It needs enough storage, the right layout, useful space, and a location that makes daily life easier. If those things are in place, many buyers are perfectly willing to trade raw square footage for lower stress and better overall fit. That is a healthier way to shop.

It is also why smaller homes are winning right now with first-time buyers, downsizers, and even move-up buyers who have looked at the full cost of owning more house and decided they would rather have a smarter home than a bigger one. Freddie Mac’s data showing first-time buyers making up more than half of purchase loans funded by the company in 2024 also fits that pattern. When first-time buyers are a larger share of activity, practical homes tend to matter more because those buyers are often more payment-sensitive and less interested in taking on unnecessary housing costs.

None of this means bigger homes are going away or that every buyer suddenly wants less space. Some families need it. Some buyers can comfortably carry it. Some properties absolutely justify it. The point is that size alone is not carrying the same weight it once did.

Buyers are thinking harder now. They are asking whether the space earns its keep. They are asking whether the payment leaves room for life. They are asking whether the home supports the way they actually live, not the way they assumed they were supposed to live.


That is a much sharper question.

And it is why smaller homes are not just surviving right now. In many cases, they are quietly outperforming because they match the market more honestly.

In This Market, Buyers Are Not Looking for Projects. They Are Looking for Easy.

A lot of sellers still think buyers want potential.

They think buyers will walk in, see past the old paint, the dated lighting, the stained carpet, the overgrown landscaping, the half-finished projects, and say, “No problem, we can make this our own.”

Some buyers will. Most will not.

Not in this market.

Right now, buyers are doing the math a lot more carefully than they were a few years ago. They are looking at the monthly payment, insurance, taxes, utilities, maintenance, and the cost of every repair they can already see coming. By the time they add all that up, a house that needs “just a little work” starts feeling a lot heavier than it looks on paper.

That is why the homes getting the best response right now are not always the newest or the fanciest. They are the ones that feel easy.

Easy to walk into. Easy to understand. Easy to imagine living in. Easy to own without immediately bleeding cash.

That shift matters.

HousingWire has been tracking the 2026 market all spring, and one of the clearest patterns has been that pricing and condition are doing more of the work now. Homes that are aligned with where buyers really are, and that do not ask buyers to take on extra stress, are moving. Homes that are overpriced or feel like projects are sitting longer and cutting price more often. (HousingWire)

That should get every seller’s attention.

Because when buyers are cautious, they are not just buying a house. They are buying a monthly reality. And if the house already feels like it comes with a to-do list, the buyer starts subtracting money immediately. They may never say it out loud, but they are doing it in their head the second they walk in.

That old carpet is going to cost something.
That roof is going to cost something.
That dark paint, those old fixtures, that neglected yard, those patched walls, that bathroom that feels tired, all of it starts turning into future expense in the buyer’s mind.

And when that happens, the house feels harder to say yes to.

Inman has been making the same point in its 2026 coverage. Buyers are not responding the way they did in the frenzy years. They are slower, more selective, and much more aware of condition. Homes that feel move-in ready are standing out because they remove friction. They do not give buyers a reason to hesitate. (Inman)

That is the key word here: friction.

A lot of sellers are still thinking in terms of upgrades, but the bigger issue right now is friction. Buyers do not need every house to be brand new. They do need it to feel manageable. There is a big difference.

A manageable house feels clean. It feels maintained. It feels like the seller cared. The lighting works. The walls are not fighting you. The spaces make sense. The smell does not distract you. The yard does not feel like a weekend job waiting to happen. The whole house feels like something you can step into without immediately making a list of what has to be fixed first.

That is what buyers want right now.

Real Estate News has also been reporting on the pressure buyers are under, especially when it comes to affordability and the added stress of ownership costs. That matters because it explains why buyers are acting the way they are. They are not being unreasonable. They are being careful. When people already feel stretched, they do not want a house that adds another layer of uncertainty. (Real Estate News)

This is exactly why some sellers get frustrated. They look at their house and think it has good bones, good space, and a good location, which may all be true. But buyers are reacting to what is in front of them today, not to what the house could become after six weekends, twelve contractors, and another twenty thousand dollars.

Potential does not hit the same when buyers feel financially tight.

Ease does.

That does not mean every seller needs to renovate. In fact, that is usually the wrong takeaway. Most sellers do not need a giant remodel. They need the house to stop creating questions. Fresh paint does that. Better lighting does that. Deep cleaning does that. Flooring fixes, yard cleanup, touch-up repairs, decluttering, and stronger presentation do that.

Those are not glamorous improvements, but they are often the ones that matter most because they make the home feel lighter.

And lighter wins.

A seller in this market has to stop asking, “What more can I add?” and start asking, “What can I remove that is making this home harder for a buyer to say yes to?”

That is a much smarter question.

Because the homes that are performing best right now are not always the ones with the most expensive updates. They are the ones that feel the least complicated. Buyers walk in and do not immediately feel burdened. They feel relief. They feel possibility. They feel like they could move forward without spending the next six months fixing what the seller left behind.

That is powerful.

And it is a lot more relevant to May 2026 than the old advice about throwing money at random upgrades and hoping buyers reward you for it.

They usually will not.

What they will reward is a home that feels cared for, clear, and easy to step into.

That is what is working right now.

Your First Offer Probably Shouldn’t Be Your Highest

Calculate Budget for Buying a Home 2

A lot of buyers walk into the offer stage thinking there are only two choices. They either come in with their very highest number right away, or they lose the house to someone else. That is a very emotional way to approach a negotiation, and it usually leads to one of two bad outcomes. Either the buyer overreaches too early, or they make a panicked decision because they assumed every listing required maximum force from the beginning.

That is exactly why your first offer probably shouldn’t be your highest unless the house, the competition, and the seller’s position clearly justify it.

The market this spring is not behaving like the frenzy years when buyers had to throw everything at a property just to stay in the running. HousingWire reported in April 2026 that price cuts were hovering around roughly one-third of listings and that there was a meaningful gap between asking prices and accepted prices, which is a strong sign that many sellers are still missing the mark on where buyers actually are. HousingWire’s broader read on the 2026 market was that pricing moves first and buyer response follows, which matters because it means many listings are not sitting in a position of total control.

Inman was making a similar point in early 2026 when it wrote about how buyers can still win in a higher-rate market. The takeaway was not that buyers should blindly swing harder. It was that they need to negotiate intelligently, look for savings, and stop assuming they have no room to work with just because rates are higher than they want them to be.

That is where buyers need to slow down and look at the actual position of the property in front of them. A home that just hit the market, shows beautifully, is priced well, and is likely to attract multiple offers is one kind of situation. A home that has been sitting, has already taken a price cut, or is competing against several similar listings is a different one. Treating those two situations the same is how buyers end up paying more than they needed to.

Real Estate News has also been pretty blunt about the tone of the 2026 market. In March, it reported that buyer stress remains high because of economic pressure and uncertainty, and that those emotions can push buyers into poor decisions and post-purchase regret if they are not careful. That is exactly the issue here. Buyers who come in at their absolute ceiling too early are often making a fear-based move, not a strategy-based one.

A good first offer should do two things at once. It should show the seller you are serious, and it should leave you room to respond if the deal starts shifting. Because deals shift all the time. Inspections uncover issues. Appraisals come in tight. Sellers counter on price, timing, or credits. If the buyer has already burned through every bit of negotiating room in the first move, the rest of the transaction gets harder than it needs to be.

That is the practical side of why your first offer probably shouldn’t be your highest. It is not just about the opening number. It is about protecting flexibility through the rest of the deal.

Real estate agent offer hand for customer sign agreement

Inman touched on this broader shift in March when it noted that negotiation has reentered the market in a real way, along with repair requests, closing cost credits, and a general return to terms actually mattering again. That is important because buyers are no longer operating in a market where every accepted offer is simply the one that came in hottest on day one. Structure matters now. Terms matter now. Leverage matters now.

Real Estate News added another useful angle in April when it wrote that buyers have an advantage in many markets this spring, especially in places where price drops are showing up and seller competition is building. That does not mean every buyer should come in low and expect a gift. It does mean buyers need to stop assuming they are always negotiating from weakness.

There is also the issue of regret, which buyers do not think about enough in the moment. It is one thing to “win” the house. It is another thing to feel good about the terms after the adrenaline wears off. Buyers who go straight to their max often have very little cushion left when something inevitably comes up later. Then a repair request feels heavier, a closing cost surprise hits harder, and the house starts feeling stressful before they even get the keys. That is not a great way to start.

A better approach is to look at the property honestly, understand the seller’s likely pressure points, and make the strongest serious offer you can make without backing yourself into a corner. Sometimes that number will be aggressive. Sometimes it will not. The point is that the decision should come from context, not panic.

So yes, there are moments when a buyer should come in very strong right away. If the property is clearly underpriced, demand is obvious, and the buyer knows losing the house would be a major setback, then the strategy changes. But that should be a deliberate choice, not the default setting for every offer.

That is the real message here. Your first offer probably shouldn’t be your highest because smart buyers do not negotiate based on nerves alone. They negotiate based on market position, property strength, seller leverage, and their own ability to stay steady through the entire transaction.

That is usually how better deals get made.

How to Know You’re Ready to Buy, Financially and Emotionally

A lot of people ask the wrong question at the beginning of the process.

They ask, “Can I buy a house?”

That is not the first question they should be asking.

The better question is, “Am I actually ready to buy a house in a way that will feel good after the excitement wears off?”

Those are two very different things. Plenty of people can get approved for a mortgage and still not be in a strong place to buy. On the other hand, some people assume they are not ready because they do not have everything lined up perfectly, when in reality they are much closer than they think. That is why it helps to look at this from both sides. Buying a home is financial, obviously, but it is emotional too. If one side is in place and the other is not, the process usually gets a lot harder than it needs to be.

The financial side starts with stability. The Consumer Financial Protection Bureau tells buyers to think in practical terms before anything else, including whether they have at least two years of steady income, manageable long-term debt, money set aside for a down payment, and room in the budget for taxes, insurance, repairs, and other ownership costs that show up after closing. The CFPB also reminds buyers that closing costs typically run about 2% to 5% of the purchase price, not including the down payment, which is exactly the kind of number people forget when they focus too much on the monthly payment alone.

That matters because a lot of buyers still look at the purchase through one narrow lens.

They see the price of the house, estimate a payment, and think they are basically there. Real life is usually a little less generous than that. The U.S. Census Bureau reported that median monthly owner costs for homeowners with a mortgage rose to $2,035 in 2024, up from $1,960 in 2023, which is a reminder that ownership costs do not sit still.

The rental side has not exactly been easy either. Census reported in January 2026 that renters paid a median of $1,413 per month in the 2020 to 2024 period, which was $100 more than in the prior five-year period, and nearly half of renter households were cost-burdened in 2023, meaning they spent more than 30% of income on housing.

That does not mean everyone should rush out and buy. It does mean buyers need to stop thinking about affordability as a one-line calculation. The real question is whether homeownership will fit your life without making everything else feel tight. If you buy and then feel stressed every month, the pride of ownership starts to wear thin pretty quickly. A good budget does not just get you into the house. It lets you live there without resenting the payment.

That is where emotional readiness comes in, and this part gets ignored far too often. A lot of buyers are financially close but emotionally scattered. They have not thought through what kind of home they really need, what trade-offs they can live with, how much uncertainty they can handle, or whether they are ready to make decisions without spiraling every time something changes. Buying a home always involves some moving parts. Inspections can uncover issues. A deal can get competitive. A lender may ask for more paperwork.

A closing timeline may shift. If every one of those things feels like a crisis, the process becomes miserable.

Emotionally ready buyers usually have a few things in common. They know their priorities. They understand that no home is perfect. They are willing to make a decision based on fit rather than fantasy. They are prepared for the fact that the process will ask something from them. That does not mean they are fearless. It means they are grounded.

It also helps to know that asking for guidance is not a weakness.

HUD encourages buyers to work with HUD-approved housing counselors for support in becoming homeowners, which can be especially useful for first-time buyers trying to understand the process without getting buried in conflicting advice. The CFPB also provides step-by-step homebuying tools that are worth using because they are practical and not built to sell you anything.

This is where buyers need to be honest with themselves. If you do not yet have a clear handle on your budget, your cash to close, or what kind of payment you can live with comfortably, you are not ready to shop seriously. If you are still wildly changing your mind about where you want to live, what you need, or how long you plan to stay, then more clarity needs to come first. If the thought of one inspection issue or one negotiation wrinkle is enough to make you want to walk away from the whole idea, then that is worth paying attention to as well.

On the other hand, if your income is stable, your debt is manageable, you have cash set aside, you understand the cost beyond the down payment, and you are ready to make a thoughtful decision without expecting everything to go perfectly, you may be much more ready than you realize.

That is really the point. Readiness is not perfection. It is not having every answer tied up in a bow. It is not waiting for some magical market moment where rates, inventory, price, timing, and your life all line up at once. It is being financially steady enough and emotionally clear enough to move forward without guessing.

Why Smaller Homes Are Winning Right Now

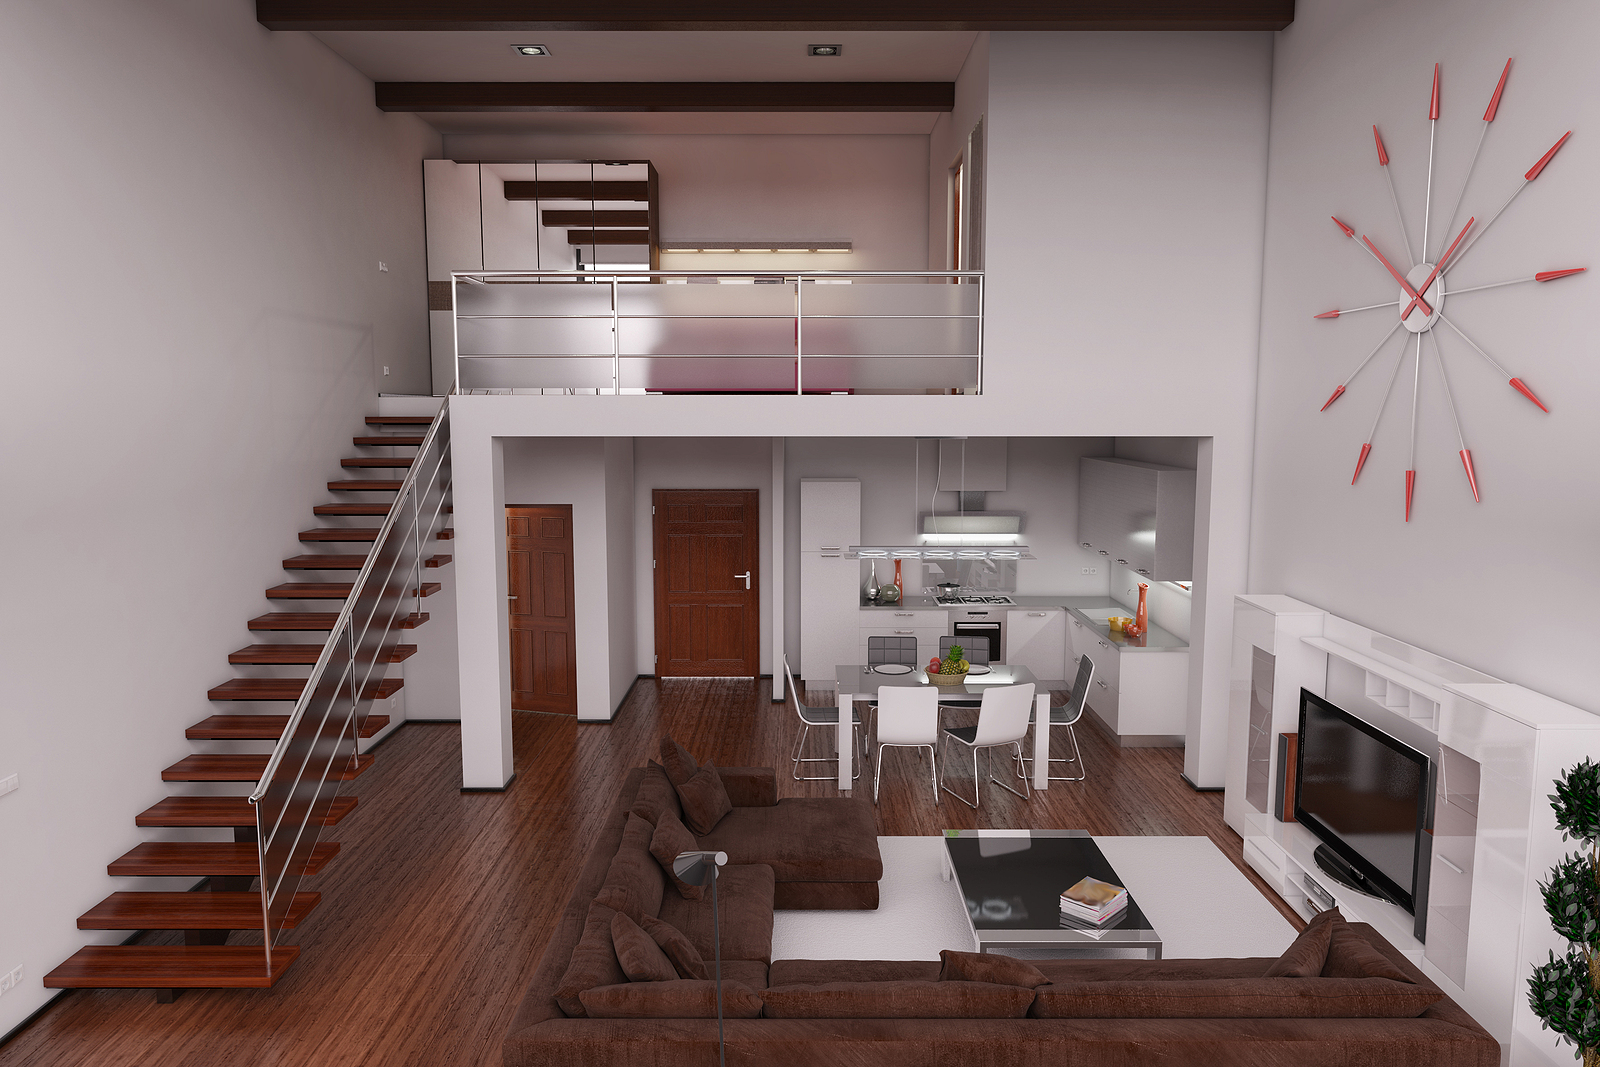
3D Interior rendering of a modern tiny loft

For a long time, bigger was the goal.

More square footage. More rooms. More storage. More space to spread out, fill up, and grow into. A larger home was often seen as the next step, the upgrade, the sign that you were moving forward.

That mindset has shifted.

A lot of buyers today are not looking for the biggest house they can afford. They are looking for the house that makes the most sense for how they actually live. That is a big reason why smaller homes are winning right now.

People are thinking differently than they used to. They are more aware of monthly costs, more aware of upkeep, and more aware that extra space is not always the same thing as better living. A house can be large and still feel wasteful, expensive, or harder to manage than it needs to be.

That is where smaller homes start making a lot more sense.

A smaller home usually costs less to buy, less to heat and cool, less to furnish, and less to maintain. That matters. Buyers are paying attention not just to the purchase price, but to the day-to-day cost of owning the home after the excitement wears off. Mortgage payments are only part of the picture. Utilities, repairs, cleaning, insurance, and upkeep all add up. More house usually means more expense in every direction.

That is one of the clearest reasons why smaller homes are winning right now. People want a home that fits their life without quietly draining their time and money.

There is also the issue of how people actually use space.

For years, buyers were sold on formal dining rooms, bonus rooms, oversized living areas, and square footage that sounded impressive on paper. But a lot of that space went underused. Rooms looked good in listing photos and then sat empty most of the year. Buyers are more aware of that now. They are asking better questions. Will we really use this room? Do we want to clean this much house every week? Are we paying for space just because it sounds nice to have it?

That kind of honesty changes the search.

Smaller homes often force better function. When space is limited, layout matters more. Storage matters more. Room purpose matters more. A well-designed smaller home can live better than a larger one with awkward flow or wasted space. Buyers are starting to see that. They would rather have a smart layout than a bunch of square footage they cannot justify.

That is another reason why smaller homes are winning right now. Buyers are paying closer attention to livability, not just size.

help for sick houseplants

Lifestyle plays a role too.

A lot of people do not want to spend their weekends maintaining a house they barely have time to enjoy. They want something easier. Easier to clean. Easier to furnish. Easier to leave for a trip. Easier to live in without constantly feeling behind on one more project. That is especially true for busy professionals, empty nesters, first-time buyers trying to stay financially comfortable, and even young families who would rather have a manageable home in the right location than a much larger one farther out.

Smaller homes also tend to make people more intentional. Less room often means less clutter, fewer unnecessary purchases, and a clearer sense of what actually matters. That may sound simple, but it changes how a home feels. A house does not have to be huge to feel good. It has to work.

And for many buyers, a smaller home works better than they expected.

That is a healthier way to buy.

It is also a big reason why smaller homes are winning right now in a lot of markets. They feel more attainable. They feel more practical. They feel less like a stretch and more like a decision buyers can live with comfortably.

There is a confidence that comes with buying a home you can truly handle. Not just on paper, but in real life. A smaller home can leave more room for savings, travel, improvements, and breathing room. It can mean less financial pressure and less daily strain. That trade-off is worth a lot more to people now than it used to be.

And honestly, a home does not need to be massive to feel meaningful.

It needs to fit your routines. It needs to support your life. It needs to give you the space you actually use, not the space you thought you were supposed to want.

That is what more buyers are figuring out.

So when people ask why smaller homes are winning right now, the answer is not complicated. They are cheaper to run, easier to maintain, and often better aligned with how people really live. They give buyers a chance to own without overreaching and to enjoy their home without constantly managing it.

That is not settling.

That is buying smarter.

Buying a Home Isn’t Just Math. It’s Confidence.

  Buying a home couple with their keys to the house happy 

A lot of people talk about buying a home like it is one big math problem.

What is the interest rate.
What is the monthly payment.
What is the down payment.
What is the tax rate.
What is the insurance cost.

Yes, all of that matters. Obviously. You should know your numbers. You should know what you can afford. You should know where your comfort level is before you even start seriously looking.

But that is not the whole story, and pretending it is usually leads people straight into bad decisions or endless paralysis.

Because buying a home is not just math. It is confidence.

A buyer can have all the numbers in front of them and still feel completely unsure. They can be approved, financially stable, and fully capable of buying, and still freeze when it is time to make a move. On the flip side, a buyer can fall in love with a house and convince themselves the numbers work when deep down they already know they are stretching too far.

That is because buying a home is not just a spreadsheet exercise. It is a decision about how you want to live, what you want your daily life to feel like, and whether you can move forward without second-guessing yourself every five minutes.

That last part matters more than people think.

A lot of buyers spend so much time chasing the perfect rate, the perfect deal, the perfect house, and the perfect timing that they completely lose sight of the bigger question. Do I feel good about this decision. Not just excited. Not just emotional. Not just relieved that I finally got an offer accepted. Do I actually feel good about it.

That is where confidence comes in.

Confidence is not recklessness. Confidence is not overpaying because you got caught up in a bidding war and decided logic was optional for the afternoon. Confidence is not ignoring red flags because the kitchen looked cute in the listing photos.

Confidence is knowing your numbers, knowing your priorities, and knowing where your line is before the pressure hits. That kind of confidence changes everything.

It means you do not walk into a house and suddenly invent a new budget because you liked the backyard. It means you do not panic when another buyer shows up. It means you do not let one pretty house throw you completely off course. It means you know what matters most to you and you can make decisions from that place instead of reacting to every little twist in the process.

And frankly, that is where a lot of buyers get themselves in trouble. They think if the math works, the decision works. Not always.

I have seen buyers qualify for a payment they absolutely hated living with. On paper, it worked. In real life, it made them feel tight every month. Suddenly dinners out felt stressful. Travel got cut. Savings slowed down. Every repair felt annoying instead of manageable. That is not a great house payment. That is a house payment that owns you.

I have also seen buyers pass on homes that made sense because they kept waiting for some magical scenario where everything felt one hundred percent certain. That does not exist either. There is no perfect market, no flawless house, and no moment where every variable lines up and angels sing while you sign the contract.

Portrait of a young woman has a question is asking herself something. Question mark over her head.

At some point, buyers have to move from analysis into decision.

That does not happen because the math got prettier. It happens because they got clearer.

That is why buying a home is so much about confidence. Confidence lets you separate what is real from what is noise. It helps you stop obsessing over every headline and start paying attention to your actual situation. It lets you look at a house and ask the right questions. Does this fit my life. Does this fit my budget. Does this fit the next few years, not just this weekend.

Confidence also keeps buyers from making emotional mistakes disguised as practical ones. Some buyers want to believe that if a lender approved them for it, it must be safe. That is not the same thing. Approval and comfort are not twins. They are cousins at best. One tells you what may be possible. The other tells you what is wise for your actual life.

That difference matters.

And then there is the confidence that comes from understanding the process itself. Buyers who know what inspections mean, what closing costs look like, how negotiations work, and what happens after an offer is accepted usually make better decisions because they are not being hit with everything at once. They are not buying in panic mode. They are buying with context.

That is what people really want, even if they do not say it that way. They want to feel steady. They want to feel informed. They want to feel like they are making a strong move, not just a desperate one.

That is why a good agent matters too. A good agent is not just there to show houses and fill out paperwork. A good agent helps clients get clear enough to move with confidence. They help buyers understand what matters, what does not, where to be flexible, and where to hold the line. They help calm the chaos so decisions stop feeling random and start feeling solid.

Because in the end, the right house is not just the one you can technically afford.

It is the one you can step into without that pit in your stomach telling you something is off.

It is the one that makes sense in real life, not just online. It is the one that works on an ordinary Tuesday, not just during an exciting showing. It is the one you can commit to without feeling like you need to talk yourself into it.

How to Make Big Real Estate Decisions Without Regret

Young couple buying a home.

One of the hardest parts of buying or selling a home is not the paperwork, the timing, or even the negotiation. It is the weight of the decision itself.

A home is not a small purchase. It is not something people change casually. It affects how you live, how you spend, how you plan, and in many cases how your family moves through daily life. That is why so many people get stuck in overthinking. They are not just trying to make a smart decision. They are trying to make the right one with no mistakes, no surprises, and no regret.

That is where things start to go sideways.

Most regret in real estate does not come from making a terrible decision. It comes from making a rushed one, an emotional one, or a vague one. It comes from not being honest about priorities. It comes from ignoring something that felt off because the pressure of the moment was louder than your own judgment.

The good news is that most regret can be reduced long before a contract is signed.

The first step is getting clear on what problem you are actually trying to solve. A lot of buyers and sellers move forward without ever slowing down enough to answer that question. They say they want a bigger home, a smaller home, a different neighborhood, more land, less upkeep, or a lower payment. Those are all valid goals, but they are not always the real issue. Sometimes the real issue is that the current home no longer fits the way life works now. Sometimes it is financial pressure. Sometimes it is a long commute. Sometimes it is the need for a fresh start.

If you are not clear on the real reason behind the move, it becomes much easier to get distracted by the wrong things.

That is where regret often begins. People focus on appearances instead of function. They get pulled toward surface features and ignore the things that will affect them every day. A beautiful kitchen can be very persuasive. So can a big backyard, a lower interest rate, or a higher offer. But none of those things matter as much if the decision itself is not solving the right problem.

The next step is being honest about trade-offs. Every real estate decision has them. Every single one. There is no version of buying or selling that comes with all upside and no compromise. The home with the perfect location may need updates. The house with more space may stretch the budget. The offer with the highest price may come with terms that make the deal riskier. The lower-maintenance condo may mean giving up privacy or storage.

People usually do not regret trade-offs they understood clearly. They regret the ones they minimized, ignored, or talked themselves out of paying attention to.
Happy family lying on floor after buying new house

That is why it helps to ask better questions before making a move. Can I live with this payment comfortably, not just technically? Does this home fit how I actually live, not just how I wish I lived? If I choose this offer, what am I really gaining and what am I giving up? If I stay where I am for another year, does that truly help me or just delay the decision?

Questions like those bring clarity fast.

Another part of avoiding regret is understanding the full cost of the decision. Buyers often focus on the mortgage and forget about everything else that comes with ownership. Sellers often focus on list price and forget about timing, repairs, concessions, fees, and the cost of carrying the house longer than expected. Real estate decisions almost always have a financial layer that is broader than the headline number.

The more complete your understanding is, the less likely you are to feel blindsided later.

Emotions matter too, and pretending they do not is a mistake. Real estate is emotional because homes are personal. People raise families in them, start over in them, celebrate in them, grieve in them, and build ordinary life inside them. Of course emotions are going to show up. The goal is not to eliminate emotion. The goal is to keep it from making the decision for you.

There is a difference between loving a home and losing perspective over it. There is a difference between wanting the highest offer and ignoring the terms attached to it. There is a difference between being excited and being swept away.

That is where good guidance matters. A good agent is not just there to open doors or write contracts. A good agent helps clients think clearly when emotions are running high. They help slow the process down where it needs to slow down and move it forward where it needs to move. They help clients look at the decision from more than one angle so they do not end up making a choice they have to unwind later.

The people who usually feel best about their decision are not always the ones who got every detail they wanted. They are the ones who understood what they were choosing, why they were choosing it, and what compromises came with it. They made a real decision, not a reactive one.

That is what reduces regret.

There is no way to remove every unknown. Real estate will always involve some level of uncertainty because life itself is uncertain. A home that feels perfect today may need to serve a very different purpose a few years from now. A market that feels difficult now may look very different later. No one gets total control over all the variables.

What people can control is how thoughtfully they make the decision in front of them.

That usually means slowing down enough to get honest, looking past the surface, understanding the numbers, and staying focused on what matters most. It means choosing based on fit, function, and long-term reality instead of pressure, noise, or fantasy.

That is how people make big real estate decisions with a lot more confidence and a lot less regret.

The Perfect Home Is a Myth, and What to Look for Instead

Calculate Budget for Buying a Home

A lot of buyers think they are looking for the one.

The perfect house. The perfect layout. The perfect street. The perfect kitchen. The perfect price.

And on paper, that sounds reasonable. Of course you want to love the home you buy. Of course you want it to feel right. Of course you want to make a smart decision.

But this is where buyers get stuck.

Because the perfect home is a myth.

how to buy a house that is not for sale 1

It does not mean there are no great homes. There are. It does not mean you should settle for something that clearly does not work. You should not. But if you go into the process thinking the right home will check every box without any trade-offs, you will either drag the search out forever or miss a house that was actually a very good fit.

That is what happens to a lot of buyers. They keep chasing a version of homeownership that only exists in their head.

The problem is not just unrealistic expectations. It is also how those expectations get built. Buyers spend hours scrolling listings, saving photos, comparing finishes, and building a running list of everything they want. Over time, that list gets longer and more specific. Then they walk into real homes and feel disappointed because the real world is not matching the version they built online.

That disconnect creates frustration fast.

It is one of the clearest reasons the perfect home is a myth. Buyers are not comparing homes to other homes anymore. They are comparing real properties to a fantasy that has no flaws, no compromises, and no price ceiling.

That is not a fair fight.

Every home comes with trade-offs. The bigger question is whether the trade-offs are ones you can live with comfortably. A house may have the right location but a smaller yard. It may have the kitchen you want but less closet space. It may check almost every box but need paint, flooring, or a few updates. That does not make it the wrong house. That makes it a real one.

The strongest buyers understand this early.

First time home buyers are shown on a business photo using the text

They stop asking whether a home is perfect and start asking whether it fits their life. That is a much smarter question. A home does not need to impress you in every category. It needs to work where it matters most.

That means figuring out your real priorities before emotion takes over.

What do you actually need day to day? Not what looks nice in listing photos. Not what would be fun to have if money were unlimited. What really matters? Commute. Layout. Bedroom count. School options. Yard space. Home office. Storage. Walkability. Quiet. Natural light. These are the things that shape daily life.

When buyers get clear on their real non-negotiables, the search gets better.

That is how you move past the idea that the perfect home is a myth and start finding homes that make practical sense. You stop expecting one property to solve everything. You start looking for the one that handles the things that matter most while leaving room for smaller imperfections you can live with.

And yes, there will almost always be imperfections.

That is not failure. That is homeownership.

Another reason buyers get tripped up is that they confuse polished with perfect. A staged home with beautiful photos and the right smell can create a strong emotional pull. That does not mean it is the right fit. At the same time, a home that shows a little less impressively online may actually have the layout, location, and long-term value that makes far more sense.

Buyers have to look past surface-level attraction.

This is where practicality matters. You can paint walls. You can update lighting. You can change fixtures, floors, landscaping, and finishes. What you cannot easily change is location, lot, floor plan, or overall function. Those are the things worth paying more attention to.

That is what to look for instead.

Instead of searching for perfect, look for strong bones. Look for a layout that fits your life. Look for a location you will still feel good about on an ordinary Tuesday, not just on the day you toured the home. Look for signs that the home has been cared for. Look for a payment you can live with comfortably. Look for a house that feels good enough now and still gives you room to grow into it.

That is a much healthier approach.

It also leads to better decisions because it takes pressure off the wrong things. Buyers who are waiting for some magical moment where the perfect house appears often miss homes that would have served them really well. They pass on good options because one bathroom is dated or the dining room is smaller than they hoped. Meanwhile, someone else buys the house and builds a very happy life there.

That happens all the time.

The truth is, the best home for you is usually not the one with zero flaws. It is the one with the right flaws. The manageable ones. The ones that do not interfere with how you live. The ones you can improve over time or simply stop noticing once the home becomes yours.

That is why the perfect home is a myth. Not because great homes do not exist, but because the real goal is not perfection. It is fit.

Happy husband and wife hugging excited to be a homeowner.

The right home should make sense financially, function well for your life, and feel like somewhere you can build from. That is more than enough.

And honestly, that is what most happy buyers end up with anyway.

Not perfect.

Just right where it counts.

Think Like an Investor, Even If This Is Your Forever Home

A lot of buyers say the same thing when they find the house they want.

“This is our forever home.”

Maybe it is. Maybe it is not.

Life changes. Jobs change. Families grow. Kids leave. Health changes. Priorities shift. What feels permanent today may not fit the same way ten years from now.

That is why it helps to think like an investor, even if you are buying a home you fully expect to keep for a very long time.

This does not mean treating your home like a cold business deal. It does not mean stripping all joy out of the process or choosing a house you do not love just because the spreadsheet says it makes sense. It means understanding that a home is both personal and financial at the same time.

The smartest buyers respect both sides.

When people hear the phrase think like an investor, they often assume it only applies to rental properties, flips, or people building wealth through real estate on purpose. But the truth is, every home purchase has long-term financial consequences whether you think about them or not.

You are putting money into an asset. You are taking on costs, risk, and responsibility. You are making decisions that affect future flexibility.

That deserves a little strategy.

One of the first ways to think like an investor is to pay attention to location in a practical way. Not just whether you personally like the street or the drive to your favorite coffee place, but whether the area has staying power. Are people drawn to it? Are there things that make it consistently desirable, such as access, schools, amenities, walkability, or stability? The features that hold value over time matter, especially if life forces a change you did not plan for.

Young couple buying a home.

A forever home still benefits from being in a place other people would want too.

Layout matters the same way.

A home can be beautiful and still be harder to sell later if the floor plan is awkward, the bedroom count is limited, or key spaces do not function well. Buyers often get distracted by finishes because countertops and fixtures are easier to notice than flow. But layout is what affects how a home lives day to day and how broadly it appeals later.

That is another reason to think like an investor. Timeless function usually holds value better than trend-driven style.

The same goes for upgrades.

A lot of homeowners pour money into improvements assuming every dollar spent increases value. It does not. Some updates are smart. Some are neutral. Some quietly make a home harder to sell because they are too personal, too expensive for the area, or too specific in taste.

Thinking strategically does not mean never improving your home. It means asking better questions before you do. Will this make the home more usable? Will it solve a real issue? Will it help the property age well? Or is it simply something I want because I like it?

There is nothing wrong with the second answer. But it helps to know the difference.

When you think like an investor, you start separating what adds lifestyle value from what adds market value. Sometimes those overlap. Sometimes they do not. That clarity helps you make stronger decisions.

Another part of this mindset is understanding monthly cost beyond the mortgage.

A home may technically fit your budget and still not be a great financial move if taxes, insurance, utilities, maintenance, and future repairs stretch you too far. Investors look at the full cost picture. Homeowners should too. A forever home should still leave room for living.

The goal is not to be house-rich and life-poor.

This matters because even a home you love can become stressful if the financial pressure is constant. That pressure limits options later. It affects how easily you can move, refinance, renovate, or adapt if life changes.

That is why it is wise to think like an investor before you buy, not after you feel stuck.

There is also the question of resale, even if you swear you will never sell.

Most people do not buy a house planning for divorce, relocation, job loss, caregiving, or unexpected opportunity. But those things happen every day. The home that felt like a forever choice can become a five-year choice or a ten-year choice very quickly.

That does not mean buying defensively. It means staying aware.

Would this home appeal to more than just me? Does it have broad strengths? If I had to sell in a different market, would it still stand out? Those are smart questions, not pessimistic ones.

When you think like an investor, you are not betting against your own future in the home. You are protecting yourself if the future changes.

And honestly, there is freedom in that.

It means you can enjoy the home you love while also knowing you bought with your eyes open. You did not just chase emotion. You paired emotion with judgment. You considered not only what feels good today, but what still makes sense tomorrow.

That is a much stronger place to buy from.

A home should absolutely feel personal. It should fit your life. It should feel like somewhere you want to wake up, host people, build routines, and make memories. But it should also make sense as an asset. Those two things are not in conflict. In fact, the best home decisions usually come from balancing both.

So yes, buy the house that feels right.

Just make sure you also think like an investor while you are doing it.

Because even if this really is your forever home, smart decisions never go out of style.